First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
Term Insurance for Parents Aged 50 to 60: Who Still Sells
Can your father or mother still buy term insurance at 54 or 59? Which plans take a new buyer at 50, 55, 60 and 65, how far the cover can run, what the insurer will ask for, why it costs so much more, and when term cover is the wrong answer.
Can a parent aged 50 to 60 still buy term insurance?
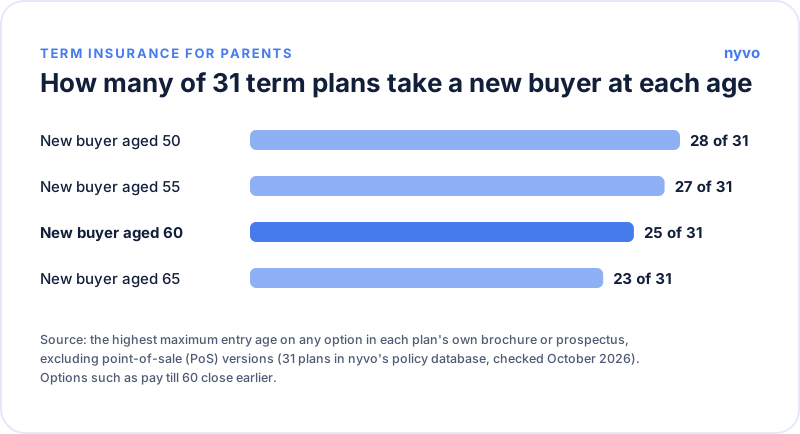
Yes. Of the 31 term plans in nyvo's policy database that we checked against each insurer's own brochure in October 2026, 28 take a new buyer at 50, 27 at 55, 25 at 60 and 23 at 65. The cover can usually run to 85. What changes after 50 is everything else: medical tests, income proof, a much higher premium and fewer plans as each plan's entry-age limit passes. Term cover is worth buying for a parent only if someone still depends on that parent's income or a loan is still running.
If your father is retired, has a pension and no one depends on his income, term insurance is usually the wrong product. His bigger risk is a hospital bill, and our guide to health insurance for parents covers that.
Back to: Term Insurance guide
Which term plans still take a buyer at 50, 55, 60 and 65?
Most term plans accept a new buyer up to 65, but a few close at 45, 50, 55 or 60. The maximum entry age here is the highest the plan allows on any option; check how the plan you are quoted defines age (many brochures use age last birthday) before comparing your parent's age with it. Some options, such as pay till 60, close earlier, and plans sold through a point-of-sale (PoS) agent usually close at 55 or 60.
| Last age a plan takes a new buyer | Plans (cover can run to) |
|---|---|
| 65 | ABSLI DigiShield (85; 100 on whole life), ABSLI Life Shield (85), ABSLI Super Term (85), Axis Max Life Smart Secure Plus (85), Axis Max Life Smart Term Plan Plus (85; 100 on Whole Life Cover), Axis Max Life Smart Total Elite Protection (85), Bajaj Life eTouch II (85; 99 on limited pay), Bajaj Life iSecure II (85), Bandhan Life iTerm Prime (85), Bharti AXA Flexi Term Pro (99), Canara HSBC iSelect Smart360 (99), Digit Glow Plus (85), HDFC Life Click 2 Protect Life (85, or whole of life), HDFC Life Click 2 Protect Super (85), HDFC Life Click 2 Protect Supreme Plus (85), ICICI Pru iProtect Smart Plus (85; 99 on whole life), Kotak e-Term (85), LIC New Jeevan Amar (80), LIC New Tech-Term (80), SBI Life Smart Shield Plus (79; 100 on whole life with limited pay), Shriram Life Flexi Shield (85; 100 on whole life), Tata AIA Maha Raksha Supreme Select (100), Tata AIA Sampoorna Raksha Promise (100) |
| 60 | Canara HSBC Young Term (99), PNB MetLife DigiProtect (85) |
| 55 | ABSLI Salaried Term (75), Shriram Life Online Term Plan (75) |
| 50 | HDFC Life Click 2 Protect Ultimate (85) |
| 45 | HDFC Life Click 2 Protect Elite Plus (85), LIC Digi-Term (75), LIC Yuva Term (75) |
Source: the eligibility table in each plan's current brochure, prospectus or sales literature, read October 2026. Two plans in our database are left out: ACKO Life Flexi Term, whose brochure states no entry age, and SBI Life eShield, which we could not confirm is still on sale.
One trap above 65. HDFC Life Click 2 Protect Supreme Plus and Click 2 Protect Super list a maximum entry age of 84 on their Life option, but for entry above 65 the brochures allow only a single premium and cap the cover at ₹50,000. For a family that needs real cover, treat 65 as the limit on these plans too.
How far can the cover run for a parent?
For a parent buying at 55 or 60, the cover can usually run to 85, which is 25 to 30 years. LIC's New Tech-Term and New Jeevan Amar stop at 80 and SBI Life Smart Shield Plus at 79 on its standard options. A few plans offer whole-life cover to 99 or 100, usually with limited premium payment and at a higher premium.
A longer cover is not automatically better at this age. Pick the cover-till age the same way at 55 as at 30: the later of the year your parent's dependants become independent and the year the last loan is paid. For a parent of 55 whose youngest child will finish college when the parent is 62, and whose home loan ends at 64, a cover to 65 or 70 does the job. Our guide to term insurance tenure works through the choice.
What will the insurer ask a parent for?
Expect a medical examination, income proof and a detailed health and habits questionnaire. IRDAI's Master Circular on Protection of Policyholders' Interests (5 September 2024) says products may require a medical examination as specified by the insurer, and that the insurer may ask for occupation and income details with proof of income to judge the ability to pay the premium. Which tests, and how much cover a given income supports, each insurer sets in its own Board-approved underwriting policy (IRDAI Master Circular on Life Insurance Products, 12 June 2024).
- Medicals. The insurer arranges the tests it needs for the age and the cover asked for. At 50 and above, assume there will be some: HDFC Life's own guide says tests are almost always required for cover of ₹50 lakh or more or for buyers over 40, and Canara HSBC Life's says a test is mandatory at age 40 or above or for cover of ₹1 crore or more.
- Income proof. Term cover replaces income, so the insurer checks there is income to replace and caps the cover at a multiple of it. Kotak Life's guide says younger applicants may get up to 25 times their annual income and older applicants a lower multiple. A parent who has stopped earning will find it hard to get meaningful cover.
- Health and habits. Declare every diagnosis, medicine, surgery and any tobacco use, including chewing tobacco. In the first three years of a life policy, a wrong answer on a material fact lets the insurer question the policy and refuse the claim (Section 45 of the Insurance Act, 1938). Our page on smoker declaration and medicals explains how insurers treat tobacco.
- Existing conditions. A condition such as diabetes or high blood pressure does not automatically mean a decline. The insurer can accept the proposal, accept it with an extra premium set under its underwriting policy, or decline it. Our guide to term insurance with pre-existing conditions covers what to prepare.
Who signs the proposal? IRDAI's Master Circular says the policyholder and the life assured "can be same or different", so a son or daughter paying for a parent's cover is not ruled out by regulation. Whether an insurer accepts a child as the policyholder on a parent's life, and whose income it counts, is its underwriting decision, so ask before you apply.
How much does term insurance cost at 55?
nyvo's published premiums stop at entry age 45, so we cannot put a figure on cover bought at 50, 55 or 60. The trend is clear from the figures we do hold: for ₹1 crore of cover till 60, a non-smoking man pays a median ₹9,528 a year at 30 and ₹22,008 at 45, 2.3 times as much (nyvo's premium data, May 2026, five plans). Ask for a quote on your parent's own age, health and cover.
The life tables show why the price climbs so steeply. On the SRS Abridged Life Tables 2020-24 (Registrar General of India), about 18 in 100 men alive at 55 die before 65. For a man of 30, it takes until 60, thirty years, to reach the same risk: about 19 in 100. A ten-year cover for a 55-year-old therefore carries roughly the risk of a thirty-year cover for a 30-year-old, packed into a third of the years, and each year's premium reflects that. Over twenty years, to 75, about 47 in 100 men alive at 55 die.
| A man buying at 55 with cover till | Men alive at 55 who die before then |
|---|---|
| 65 | About 18 in 100 |
| 75 | About 47 in 100 |
| 85 | About 78 in 100 |
Arithmetic on the SRS Abridged Life Tables 2020-24, India, men (Registrar General of India, May 2026): the share dying before each age is 100 × (1 − number alive at that age ÷ number alive at 55). These are population figures; insurers price from their own data on the people they insure, so read them as the shape of the risk, not a premium.
When is term insurance the wrong answer for a parent?
When no one depends on the parent's income and no loan would fall on the family. Term insurance replaces income for the people who would lose it. It is the wrong buy for a parent who:
- Has retired and lives on a pension or savings that continue after death, for example to a spouse.
- Has no dependants: the children are earning and the spouse has their own income or assets.
- Is buying it as an investment. A plain term plan pays nothing if your parent outlives it, and a return-of-premium variant gives back only the premiums, with no interest.
It is the right buy when a parent of 50 to 60 still earns and the family would struggle without that income: a younger child still in school or college, a spouse with no income, or a home loan or business loan that would fall on the family. If a loan is the only reason, cover that falls with the loan balance is one option; our guide to level vs decreasing term cover sets out what you give up.
For most retired parents, the money is better spent on health cover. A super top-up for parents can raise their hospital cover when the base policy cannot grow.
FAQs
Can I buy term insurance for my father aged 55?
Yes, on most plans. Of the 31 term plans we checked in October 2026, 27 take a new buyer at 55 and 25 at 60. Expect a medical examination and income proof, and buy it only if someone still depends on your father's income or a loan is running.
What is the maximum age to buy term insurance in India?
65 on most plans. Of the 31 term plans we checked, 23 take a new buyer at 65. Two HDFC Life plans list 84 on one option, but above 65 they allow only a single premium and at most ₹50,000 of cover.
How long can term cover run if my parent buys at 60?
Usually to 85, which is 25 years. LIC's New Tech-Term and New Jeevan Amar stop at 80, and some plans offer whole-life cover to 99 or 100 at a higher premium.
Is a medical test compulsory for term insurance after 50?
Usually, yes. Each insurer sets its tests by age and cover in its underwriting policy, and insurers' own guides put the line lower than 50: HDFC Life says tests are almost always required over 40, and Canara HSBC Life says they are mandatory from 40.
Can a retired parent buy term insurance?
It is hard and rarely worth it. Insurers can ask for proof of income to judge the ability to pay, and term cover exists to replace income. A retired parent with no dependants usually needs health insurance far more.
How much does term insurance cost at 55?
nyvo's published premiums cover entry ages 25 to 45 only, so we do not quote a figure at 55. At 45, a non-smoking man pays a median ₹22,008 a year for ₹1 crore of cover till 60, 2.3 times the price at 30 (nyvo's premium data, May 2026). Get a quote on your parent's own health and age.
Can I be the policyholder on my parent's term plan?
IRDAI allows the policyholder and the life assured to be different people, but each insurer decides whom it accepts as policyholder on a parent's life and whose income it counts. Ask the insurer before you apply.
Related Guides
Sources:
- Each plan's current brochure, prospectus or sales literature, eligibility tables read October 2026 (31 plans, listed in the table above)
- IRDAI Master Circular on Protection of Policyholders' Interests, 2024, Ref IRDAI/PP&GR/CIR/MISC/117/9/2024, 5 September 2024
- IRDAI Master Circular on Life Insurance Products, Ref IRDAI/ACTL/MSTCIR/MISC/89/6/2024, 12 June 2024
- Section 45 of the Insurance Act, 1938, as amended by the Insurance Laws (Amendment) Act, 2015
- Office of the Registrar General & Census Commissioner, India: SRS Based Abridged Life Tables 2020-24, May 2026
- nyvo's premium data, May 2026: ₹1 crore cover till 60, non-smoker, five plans
Disclaimer: Educational content only. Eligibility changes when an insurer refiles a plan; check the brochure for the version you are quoted.
Our editorial principles
- Salaried advisors, not commission-linked: we focus on clarity and suitability, not product hype.
- No spam: we don't sell your data; we keep advice simple and actionable.
- Claims-first: policy features are evaluated by how they behave during claims.
- Education-first: this content is for informational purposes only.
Term insurance after 50 at a glance
| Plans taking a new buyer at 50 | 28 of 31 checked plans (insurers' brochures, October 2026) |
|---|---|
| At 55 | 27 of 31 checked plans (insurers' brochures, October 2026) |
| At 60 | 25 of 31 checked plans (insurers' brochures, October 2026) |
| At 65 | 23 of 31 checked plans (insurers' brochures, October 2026) |
| Above 65 on HDFC Life | Click 2 Protect Supreme Plus and Super list 84 on the Life option, but only as a single premium for at most ₹50,000 of cover (HDFC Life brochures, 2026) |
| How far cover runs | To 85 on most plans; 80 on LIC's New Tech-Term and New Jeevan Amar; 99 or 100 on some whole-life options (insurers' brochures, October 2026) |
| Men alive at 55 who die before 65 | About 18 in 100; before 75, about 47 (arithmetic on SRS Abridged Life Tables 2020-24, May 2026) |
| nyvo's published premiums | Entry ages 25 to 45 only, cover till 60; nothing for 50 or above (nyvo's premium data, May 2026) |
| Proof the insurer may ask for | Income details with proof of income, and a medical examination where the product requires it (IRDAI Master Circular on Protection of Policyholders' Interests, 5 September 2024) |
Entry ages are the highest a plan allows on any option, outside point-of-sale (PoS) versions; some options, such as pay till 60, close earlier.
Book a call for advice on the best policy for you and your family
A salaried, IRDAI-certified nyvo advisor will look at your cover, flag the gaps that matter, and tell you plainly what to fix. No commission, no pressure.
A first in India
Buy policy from nyvo insurance with Claim Support Guarantee, otherwise money back.
Alumni of IIT Delhi and IIM Ahmedabad. Former consultant at BCG and part of the strategy team of slice. Founder of nyvo and IRDAI Certified Insurance Advisor.