First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
Health Insurance for Parents Above 50: Plans and PED Waits
Health insurance for parents above 50 with BP or diabetes turns on one number: the pre-existing-disease wait. The law caps it at 36 months (IRDAI (Insurance Products) Regulations, 2024), several plans cut it to 12 for an extra premium, and named-condition add-ons cover BP and diabetes within about a month, if the condition is declared.
Written by Harsh SoniReviewed by Kshitij JainUpdated nyvo insurance Services LLP, IRDAI Corporate Agent (Composite) CA1085Salaried advisors, no commission-based ranking
Insuring parents above 50, at a glance
| Legal ceiling on the pre-existing wait | 36 months, under the IRDAI (Insurance Products) Regulations, 2024, effective 1 April 2024 |
|---|---|
| Shortest standard wait for an older entrant | 12 months on Care Senior Health Advantage and Star Red Carpet (each plan's wording, read October 2026) |
| General reduction you can buy | to 12 months on Care Supreme, ICICI Lombard Elevate, Niva Bupa ReAssure 3.0 and Aditya Birla Activ One (each plan's prospectus or wording, read October 2026) |
| BP and diabetes within about a month | Activ One Chronic Care from day 1; Care Supreme Instant Cover and Elevate Jumpstart from day 31; HDFC ERGO ABCD Chronic Care after 30 days (each plan's wording or customer information sheet, read October 2026) |
| No upper entry age | Optima Secure Plus, Activ One, Care Supreme, Care Senior Health Advantage (Premium) and Golden Shield; ReAssure 3.0 takes entrants to 99; Senior First and Red Carpet close at 75 (each plan's prospectus or brochure, read October 2026) |
| Co-pay on plans for older buyers | 30% of every claim on Red Carpet; 50% by default on Senior First and Golden Shield, reducible for extra premium (each plan's wording or prospectus, read October 2026) |
| If an insurer declines | it must give its reasons within 7 days (IRDAI Master Circular on Protection of Policyholders' Interests, 5 September 2024) |
| PM-JAY at 70 and above | up to ₹5 lakh a year on a family basis, irrespective of income, plus a separate top-up of up to ₹5 lakh for a 70-plus member of a family already covered (Union Cabinet decision, PIB, 11 September 2024) |
Plan terms come from each insurer's own prospectus, policy wording or customer information sheet, read in October 2026; the wording you are issued governs. Every shortcut covers only a condition you declared and the insurer accepted.
Health insurance for a parent aged 50 to 70 who already has BP, diabetes or a past surgery comes down to one number most comparisons skip: the pre-existing-disease wait your parent will actually serve. The law caps that wait at 36 months, under the IRDAI (Insurance Products) Regulations, 2024, effective 1 April 2024. Several plans cut it to 12 months for an extra premium, and named-condition add-ons cover BP and diabetes from day 1 or after about 30 days, if the condition is declared and accepted. This guide sets those waits out plan by plan, with entry age and co-pay, from each insurer's own wording.
Price is the other number. On nyvo's own premium data (720 quotes, April 2026), ₹10 lakh of individual cover costs ₹7,000–14,500 a year at 30 and ₹32,000–48,000 at 61, about 3.3 to 4.6 times as much comparing the ends of each range, so the plan structure you choose matters more than the brand. To see the range at your parent's age, use the health insurance premium calculator.
What changes when you insure a parent above 50?
Insuring a parent above 50 differs from insuring yourself on three counts: the premium is higher (₹10 lakh of individual cover costs ₹32,000–48,000 a year at 61 against ₹7,000–14,500 at 30 on nyvo's April 2026 premium data), a pre-existing condition is likely, and most plans written only for older buyers carry a co-pay. What does not change is the legal ceiling on the pre-existing wait, 36 months at every age under the IRDAI (Insurance Products) Regulations, 2024.
| Factor | Young adults (25–35) | Parents (50–70) |
|---|---|---|
| Annual premium, ₹10 lakh individual | ₹7,000–14,500 at 30 | ₹32,000–48,000 at 61 |
| Pre-existing conditions | Less likely | Likely: BP, diabetes, a past surgery |
| Pre-existing wait | Rarely matters | Decides when the main risk is covered: up to 36 months |
| Co-pay | None compulsory on mainstream plans | None compulsory on the mainstream plans below; 30% to 50% of every claim on several plans written for older buyers |
| Medical tests before cover | Often none | More likely: Care Supreme asks for tests from 66, and may ask at any age once a condition is declared |
| Entry age | Open | Open on mainstream plans; Senior First and Red Carpet close at 75 |
Premiums are annual ranges from nyvo's own premium data (720 quotes, April 2026), taken across 10 metro and non-metro pincodes and four leading health plans, each range spanning every city and plan. Plan terms are from each plan's own documents, read in October 2026.
How long will a parent with BP or diabetes wait, plan by plan?
What this video covers (9 chapters)
- 0:00Health Insurance for Parents 50+: Can They Still Get It
- 0:23Case 1: Parents Who Are Fit and Fine
- 0:38Case 2: BP, Diabetes, Cholesterol or Asthma
- 0:54Case 3: After Cancer or a Heart Attack
- 1:06Waiting Period, Disclosure and the Limits to Avoid
- 1:34How to Buy: Individual, Family Floater or Corporate
- 2:002 Ways to Lower the Premium for Senior Citizens
- 2:24The Deductible Option: Rs 25,000 or Rs 50,000
- 2:45Don't Wait: Buy Before a Diagnosis
On the plans parents most often buy, the standard pre-existing wait is 36 months on mainstream plans and 12 or 24 months on the four plans written for older buyers in the table below. A paid option cuts the general wait to 12 months on Aditya Birla Activ One, Care Supreme, ICICI Lombard Elevate and Niva Bupa ReAssure 3.0, and named-condition add-ons cover BP and diabetes from day 1 or after about 30 days.
| Plan | Entry age for a parent | Standard pre-existing wait | Shortest with the plan's general option | BP and diabetes route | Co-pay for an older entrant |
|---|---|---|---|---|---|
| HDFC ERGO Optima Secure Plus | 18 and over, no maximum | 36 months | None you can choose (see below) | ABCD Chronic Care add-on: asthma, blood pressure, cholesterol and diabetes, covered after 30 days | None |
| Aditya Birla Activ One MAX | 18 and over, no maximum | 3 years | 2 years or 1 year, first policy only | Chronic Care add-on: both waits waived for seven listed conditions, diabetes and hypertension among them | None |
| Aditya Birla Activ One VYTL | 18 and over, no maximum | 3 years | 2 years or 1 year, for conditions outside the chronic list | Chronic Care built in: the same seven conditions covered from day 1 | None |
| Care Supreme | 18 and over, no maximum | 36 months | 24 or 12 months | Instant Cover: diabetes, hypertension, hyperlipidaemia and asthma from day 31, first Care policy only | None in the base plan |
| ICICI Lombard Elevate | No practical limit (125 in its prospectus) | 36 months | 24 or 12 months, kept for 3 policy years | Jumpstart: six listed conditions, diabetes and hypertension among them, from day 31 | None as standard |
| Niva Bupa ReAssure 3.0 Black | 18 to 99 | 36 months | 24 or 12 months, chosen at purchase only | None | None on Black |
| Care Senior Health Advantage (Premium) | 60 and over, no maximum | 12 months | 12 months is the standard | Instant Cover waives the pre-existing wait for declared and accepted diabetes, hypertension, hyperlipidaemia and asthma, first Care policy only | None compulsory |
| Niva Bupa Senior First | 61 to 75 | 24 months | No reduction option | None | 50% by default; 40%, 30% or 20% for extra premium |
| Star Health Senior Citizens Red Carpet | 60 to 75 | 12 months | No reduction option | None | 30% of every claim |
| ICICI Lombard Golden Shield | 56 and over, no maximum | 24 months | No reduction option | None | 50%, reducible for extra premium |
Each row is from the plan's own document, read in October 2026: HDFC ERGO's my: Optima Secure prospectus (UIN HDFHLIP26058V082526) and ABCD Chronic Care customer information sheet (HDFHLIA25044V012425); the Activ One MAX and VYTL policy wordings (ADIHLIP24097V012324); the Care Supreme (CHIHLIP27061V032627) and Senior Health Advantage (CHIHLIP22223V012122) prospectuses; ICICI Lombard's Elevate wording (ICIHLIP27057V062627) and Golden Shield prospectus (ICIHLIP25042V022425), with Elevate's entry age from nyvo's policy database; Niva Bupa's ReAssure 3.0 (NBHHLIP26047V012526) and Senior First (NBHHLIP27053V022627) prospectuses; and Star's Red Carpet wording and brochure (SHAHLIP26041V082526).
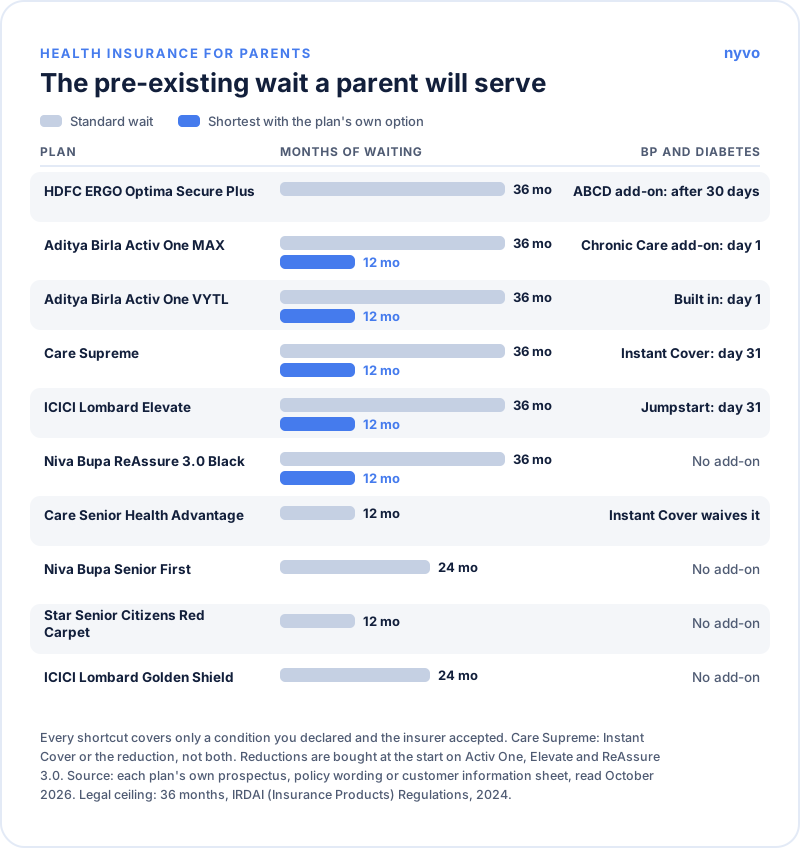
Read the table with five rules from the wordings themselves:
- Only a declared, accepted condition is covered. Every wording above pays for a pre-existing disease after the wait only if it was declared on the proposal form and accepted by the insurer, and each BP and diabetes route covers only a condition the insurer has accepted. Hiding a condition saves no time; it puts the cover for that condition at risk.
- A condition on two lists waits the longer time. Where a condition sits on both the named-illness list and the pre-existing list, the longer of the two waits applies (Optima Secure and Red Carpet wordings say so in terms). A joint replacement for a parent with a known knee problem is one example.
- Extra cover waits afresh. Raise the sum insured later and the pre-existing wait starts again on the increase. Activ One's and Elevate's reductions apply only to the sum insured chosen when the policy began.
- The two Care routes do not combine. On Care Supreme you take Instant Cover or the 24- or 12-month reduction, not both. Senior Health Advantage also sells an option that lengthens its 12-month wait to two or three years in exchange for a lower premium; check your quote has not switched it on.
- Optima Secure Plus has no reduction a buyer can pick. HDFC ERGO's live prospectus adds a 24- or 12-month option, but it says the option is set "at channel level only" at the start of the policy and that policyholders cannot opt for it. For a parent with BP or diabetes, the route you can choose is the ABCD Chronic Care add-on.
Our guide to day-1 cover for pre-existing diseases explains how these add-ons are priced and how to tell a true day-1 benefit from a reduced wait. How each of the four clocks runs is in waiting periods explained.
What happens to a pre-existing-disease add-on after the standard wait ends?
Once 36 months of continuous cover have passed, the standard pre-existing wait in every wording above has ended on the sum insured you started with, so a reduction option has nothing left to shorten there; any increase in sum insured carries its own wait. Whether you can then drop the option is set plan by plan, and on several plans you cannot: the wordings below decide, not the sales pitch.
| Plan and option | What the insurer's own wording says |
|---|---|
| Niva Bupa ReAssure 3.0, pre-existing wait modification | Chosen only when you buy; it cannot be added, changed or removed at a renewal |
| HDFC ERGO my: Optima Secure, pre-existing wait modification | Set at the start of the policy only; once selected, it cannot be opted out for the life of the policy |
| ICICI Lombard Elevate, waiting period reduction | Available only at the start, for the sum insured chosen then, and must be kept for 3 continuous policy years |
| Aditya Birla Activ One, Chronic Care | Cover for an accepted chronic condition cannot be deleted at later renewals |
| Aditya Birla Activ One, pre-existing reduction | Only at the start of the first policy, and only for the sum insured chosen then |
| Care Supreme, wait modification and Instant Cover | Optional benefits can be added at the start or at a renewal, but one added at a renewal starts its waiting periods afresh from that renewal; Instant Cover is for your first policy with Care only |
Two consequences follow. First, the decision belongs at the first purchase: most of these options cannot be bought later, and an option added at a renewal on Care Supreme starts its own clock. Second, porting carries the time your parent has served, not the shorter wait. The acquiring insurer's wording reduces its own wait to the extent of prior coverage, so a parent who ports after 12 months from a plan with a 12-month wait into a plan with a 36-month wait would, on that wording's terms, still face the balance. Ask the new insurer to confirm the remaining wait in writing before you port. How porting works covers the rest.
Which mainstream plan suits your parent?
Parents over 60 have the same options as any senior buyer: our guide to senior citizen health insurance covers the rules, and our list of the best plans for senior citizens sets out the ones we recommend. Five mainstream plans take a parent at any practical age with no compulsory co-pay.
| Plan | Entry age | Sum insured | Pre-existing wait | Insurer record (CSR · complaints/10k) |
|---|---|---|---|---|
| HDFC ERGO Optima Secure Plus | 18 and above, no upper limit | ₹10 lakh to ₹2 crore | 36 months | 97.8% · 8.3 |
| Aditya Birla Activ One MAX | 18 and above, no maximum entry age | ₹2 lakh to ₹6 crore | 3 years, reducible to 2 or 1 | 96.5% · 18.2 |
| ICICI Lombard Elevate | No practical bar (125 in its prospectus) | From ₹5 lakh, no stated maximum | 36 months, reducible to 24 or 12 – and from day 31 for six conditions under Jumpstart | 87.6% · 16.6 |
| Care Supreme | 18 and above, no upper limit | ₹5 lakh to ₹6 crore | 36 months, reducible to 24 or 12 | 96.0% · 42.9 |
| Niva Bupa ReAssure 3.0 | 18 to 99 | ₹5 lakh, ₹10 lakh or Unlimited | 36 months, reducible to 24 or 12 if chosen at purchase | 93.3% · 35.4 |
Claim and complaint ratios: IRDAI published data, a weighted average of the last three financial years, latest available as of March 2026; complaints are per 10,000 claims.
All five renew for life with no cover-ceasing age. Since the IRDAI Master Circular on Health Insurance Business of 29 May 2024 removed the maximum entry age, these plans accept a 68-year-old, and they are usually the better buy than a plan with "senior" in its name. Compare what you give up on the plans written for older buyers:
| Mainstream plans above | Plans for older buyers | |
|---|---|---|
| Co-payment | None in the base plan | 30% on Red Carpet; 50% by default on Senior First and Golden Shield |
| Sum insured ceiling | ₹2 crore to ₹6 crore, or Unlimited | ₹25 lakh on Senior First and Red Carpet, ₹50 lakh on Golden Shield, ₹3 crore on Care Senior Health Advantage |
| Standard pre-existing wait | 36 months | 12 months on Care Senior Health Advantage and Red Carpet, 24 months on Senior First and Golden Shield |
Underwriting still applies at any age. Care Supreme, for example, asks for no medical test up to 65 when no pre-existing condition is declared, and for a set of tests from 66; once a condition is declared it may ask for tests at any age (Care Supreme prospectus).
How to choose between the five:
- HDFC ERGO Optima Secure Plus if the claim experience matters most. HDFC ERGO settles 97.8% of claims and draws 8.3 complaints per 10,000 claims (IRDAI published data, three-year weighted average, latest as of March 2026), the strongest record of the five, though not the market's lowest.
- ICICI Lombard Elevate if pre-existing conditions are the problem. Its wait reduces to 12 months as an option, and Jumpstart covers six named conditions from day 31 once the insurer accepts them. On the same IRDAI data, ICICI Lombard settles the smallest share of the five, 87.6%, though its 16.6 complaints per 10,000 claims is lower than Care Health's 42.9 or Niva Bupa's 35.4.
- Aditya Birla Activ One MAX for a parent with a chronic condition: its Chronic Care add-on waives the pre-existing and initial waits for seven named conditions, diabetes and hypertension among them, and cover runs to ₹6 crore. Activ One VYTL builds the same chronic cover in.
- Care Supreme for cover to ₹6 crore that refills without limit within a policy year, same illness included. Care Health draws 42.9 complaints per 10,000 claims on the same IRDAI data, the heaviest of the five, which is the trade.
- Niva Bupa ReAssure 3.0 for the Unlimited sum insured option, if the ceiling is what worries you.
Which co-pays apply when a parent joins late?
None of the mainstream plans in this guide carries a compulsory co-pay at any entry age; a co-pay appears there only if you choose one, such as a voluntary co-pay or a restricted hospital list, to cut the premium. The compulsory co-pays sit on plans written for older buyers and on some family plans: 20% of every claim on Star Family Health Optima for anyone joining at 61 or above, 30% on Star Red Carpet, and 50% by default on Niva Bupa Senior First and ICICI Lombard Golden Shield.
Plan by plan, from each insurer's own wording:
- Star Family Health Optima: 20% of every claim, on the first policy and every renewal, for anyone whose entry age is 61 or above (policy wording, UIN SHAHLIP26046V092526).
- Star Senior Citizens Red Carpet: 30% of all claims (policy wording, SHAHLIP26041V082526).
- Niva Bupa Senior First: 50% by default, which you can lower to 40%, 30% or 20% for extra premium, but only when you first buy; it cannot be changed later. A room above your eligible category adds 10 percentage points. If you choose the optional annual deductible of one-fifth of the sum insured, it replaces the co-pay, except for that room-category addition (prospectus, NBHHLIP27053V022627).
- ICICI Lombard Golden Shield: 50% of every admissible claim, reducible for extra premium. A reduction made at a renewal carries fresh waiting periods on the reduced portion (prospectus, ICIHLIP25042V022425).
- HDFC ERGO Optima Senior: 15% in a shared room and 30% in a single room or higher, and 30% on a listed set of procedures including cataract and joint replacement (policy wording, HDHHLIP21379V022021).
- Care Senior Health Advantage: no compulsory co-pay. A 20% co-pay applies outside its Annexure III hospital list only if you choose the premium-cutting Smart Select option, and a voluntary co-pay, if you choose one, rises by 10 percentage points once the entry or renewal age is above 70 (prospectus, CHIHLIP22223V012122).
Example: a parent is hospitalised for ₹5 lakh. With a 20% co-pay, you pay ₹1 lakh out of pocket.
| Co-pay | You pay on a ₹3 lakh claim | You pay on an ₹8 lakh claim |
|---|---|---|
| 0% (no co-pay) | ₹0 | ₹0 |
| 10% | ₹30,000 | ₹80,000 |
| 20% | ₹60,000 | ₹1.6 lakh |
| 30% | ₹90,000 | ₹2.4 lakh |
| 50% | ₹1.5 lakh | ₹4 lakh |
Look for no co-pay or a low one for parents. Care Supreme and HDFC ERGO Optima Secure Plus carry no co-pay in the base plan, whatever the parent's entry age. The mechanics, with a worked claim, are in how a co-pay works.
What if one insurer declines your parent?
A decline from one insurer is not a decline from all. Each insurer underwrites under its own board-approved underwriting policy (IRDAI Master Circular on Health Insurance Business, 29 May 2024, Chapter II), and an insurer that does not accept a proposal must tell you its decision, with reasons, within 7 days (IRDAI Master Circular on Protection of Policyholders' Interests, 5 September 2024). Work through these steps in order.
- Get the reason in writing. The reason tells you whether the problem is a test result, a recent admission, the sum insured or the condition itself, and which of the routes below is worth trying.
- Try a second mainstream insurer, and a plan built for the condition. Activ One VYTL covers seven chronic conditions from day 1 once accepted, Elevate's Jumpstart covers six from day 31, and Care Supreme's Instant Cover covers four from day 31 on a first Care policy. Each still needs the condition accepted, so declare it in full.
- Move to the plans written for older buyers. They exist for this case, and they price access through the wait, the co-pay or both:
| Plan | Entry | Sum insured | Pre-existing wait | Co-pay |
|---|---|---|---|---|
| Care Senior Health Advantage | 45 to under 60 (Elite); 60 and above, no upper limit (Premium) | ₹1 lakh to ₹3 crore | 12 months | None compulsory |
| Star Health Senior Citizens Red Carpet | 60 to 75 | ₹1 lakh to ₹25 lakh | 12 months | 30% of every claim |
| Niva Bupa Senior First | 61 to 75 | ₹5 lakh or ₹10 lakh (Gold); ₹5 lakh to ₹25 lakh (Platinum) | 24 months | 50% by default |
| ICICI Lombard Golden Shield | 56 and above, no upper limit | ₹3 lakh to ₹50 lakh | 24 months | 50%, reducible for extra premium |
| HDFC ERGO Optima Senior | 61 and above | ₹2, ₹3 or ₹5 lakh | 36 months | 15% to 30% by room type |
- Keep any existing cover running. Do not cancel a parent's current policy, or let employer cover lapse, until a new policy is issued: a break ends the continuity a later port would rely on.
- Add height with a super top-up if the base insurer will not give the sum insured you want. Our guide to a super top-up for parents covers that route.
- For a parent aged 70 or over, enrol in PM-JAY as well (see below). It sits alongside a private policy; it does not replace one.
Care Senior Health Advantage is worth naming for one reason: a 12-month pre-existing wait, a third of the 36 months the mainstream plans carry as standard, with no compulsory co-pay. The cost is Care Health's 42.9 complaints per 10,000 claims (IRDAI published data, three-year weighted average, latest as of March 2026) and room limits on smaller covers: below ₹5 lakh, room rent is capped at 1% of the sum insured a day.
Never re-apply on a form that leaves out the condition behind the decline. The standard clause covers a pre-existing condition after the wait only if it was declared and accepted, and how to disclose a pre-existing disease shows how to declare one properly.
How much cover do parents need?
| Parent's situation | Recommended cover |
|---|---|
| Age 50–60, no major pre-existing conditions | ₹10–15 lakh |
| Age 50–60, with diabetes or BP | ₹10–15 lakh + super top-up |
| Age 60–65, metro city | ₹15–25 lakh |
| Age 65–70, several pre-existing conditions | ₹10 lakh + super top-up |
| Age 70+ | Any of the five mainstream plans above – all accept entry at this age – plus a super top-up |
What that costs: on nyvo's own premium data (720 quotes, April 2026), ₹10 lakh of individual cover is ₹32,000–48,000 a year at 61 and ₹20 lakh is ₹44,000–67,000. The data stops at an eldest age of 66, so ask for a quote on your parent's own age and city beyond that.
Don't under-insure parents to save premium. Treat ₹10 lakh as the floor for a parent's base cover, and size a super top-up against the hospitals your parent would actually use.
If a parent still earns and the family depends on that income, health cover is only half of it: see term insurance for parents aged 50 to 60.
Should you add parents to your floater?
Almost never. Adding parents to a young family's floater:
- Raises the premium sharply, because a floater is priced on the eldest member's age
- Shares one sum insured between four to six people, so one parent's admission can exhaust the family's cover
- Limits plan choice: Care Supreme's floater, for example, takes at most two adults and two children, so two parents cannot be added to a floater that already covers you and your spouse
Better approach: a separate policy for parents plus your own family floater. That isolates the premium and keeps one person's claim from eating into everyone else's cover.
Read family floater vs individual.
Is a government scheme enough for a parent over 70?
Ayushman Bharat PM-JAY now covers every Indian aged 70 and above, irrespective of income, with up to ₹5 lakh a year on a family basis, and a separate top-up of up to ₹5 lakh a year for a 70-plus member of a family the scheme already covers (Union Cabinet decision, Press Information Bureau, 11 September 2024). A parent aged 55 to 69 does not qualify under that decision.
Treat it as a layer, not the plan. The same decision says seniors with private health insurance remain eligible, and those in CGHS, ECHS or Ayushman CAPF may keep their scheme or choose PM-JAY. Its cover is up to ₹5 lakh a year on a family basis, plus that separate top-up of up to ₹5 lakh for a 70-plus member of a family already covered, so a retail plan is still what gives your parent a higher sum insured and the insurer's own hospital network. Our guide to health insurance after 70 covers what else changes at that age.
What tax deduction do you get for parents' premium?
Under Section 80D of the Income-tax Act, 1961 (section 126 of the Income-tax Act, 2025, from tax year 2026-27), in the old tax regime, you can deduct up to ₹25,000 a year for your parents' health insurance premium, or ₹50,000 if either parent is a senior citizen. This is on top of the ₹25,000 for your own family (₹50,000 if you or your spouse is a senior citizen). Preventive health check-ups count within these limits, up to ₹5,000 (Income Tax Department, guide for salaried individuals, AY 2026-27).
| Parent's age | Your deduction for their premium |
|---|---|
| Below 60 | Up to ₹25,000 |
| 60 or above | Up to ₹50,000 |
If your parents are above 60, the combined deduction reaches ₹75,000 a year (₹25,000 for your own family plus ₹50,000 for senior parents). It reaches ₹1,00,000 only if you or your spouse are also 60 or above. Read Section 80D tax benefits.
How does a super top-up help when you insure parents?
A super top-up pays only above a deductible you choose, which is why it is the cheaper way to add height to a parent's cover:
- Base plan: ₹10 lakh from a reputable insurer (₹32,000–48,000 a year at 61 on nyvo's own premium data, 720 quotes, April 2026)
- Super top-up: ₹50 lakh with a ₹10 lakh deductible, priced below a base plan of the same size because it pays only above the deductible
- Total cover: ₹60 lakh
Set that against a standalone ₹50 lakh plan, which costs ₹52,500–77,500 a year at 61 on the same data, and ask for both quotes on the same age and city before you choose. Read base vs super top-up explained, and our guide to a super top-up for parents when the base insurer will not raise the sum insured.
Back to: Health Insurance Guide | Senior Citizen Guide
Need to insure your parents? A nyvo advisor will read the wordings with you, match the plan to your parents' age, conditions and city, and tell you which wait-reduction option, if any, is worth its premium.
FAQs
What is the best health insurance for parents above 60?
For most parents above 60, a mainstream plan with no compulsory co-pay and no upper entry age: HDFC ERGO Optima Secure Plus for the strongest claim record, Aditya Birla Activ One MAX or VYTL, or ICICI Lombard Elevate, for diabetes or BP, and Care Supreme for unlimited refills. Care Senior Health Advantage, with a 12-month pre-existing wait and no compulsory co-pay, is the first fallback if those decline.
How long is the pre-existing disease waiting period for parents?
At most 36 months, the cap in the IRDAI (Insurance Products) Regulations, 2024. Mainstream plans use 36 months as standard and sell options that cut it to 12; Care Senior Health Advantage and Star Red Carpet wait 12 months, and Niva Bupa Senior First and ICICI Lombard Golden Shield 24.
Can a parent with diabetes or BP be covered within a month?
Yes, through a named-condition add-on, once the insurer accepts the declared condition. Aditya Birla Activ One's Chronic Care covers it from day 1, Care Supreme's Instant Cover and ICICI Lombard Elevate's Jumpstart from day 31, and HDFC ERGO's ABCD Chronic Care after a 30-day wait.
Does a PED reduction rider stay after the three-year wait ends?
Often it must. Niva Bupa ReAssure 3.0's option cannot be removed at renewal, HDFC ERGO's cannot be opted out for the life of the policy, Aditya Birla's Chronic Care cannot be deleted at renewal, and ICICI Lombard Elevate's reduction must be kept for 3 continuous policy years. Once 36 months have passed, the standard wait has ended on the original sum insured anyway; an increase carries its own wait.
What should I do if an insurer declines my parent?
Ask for the reasons, which the insurer must give within 7 days under IRDAI's Master Circular on Protection of Policyholders' Interests (5 September 2024), then apply to another insurer, because each underwrites under its own policy. Plans written for older buyers, such as Care Senior Health Advantage, Star Red Carpet, Niva Bupa Senior First and ICICI Lombard Golden Shield, exist for exactly this case.
How much does health insurance for parents cost?
On nyvo's own premium data (720 quotes, April 2026), ₹10 lakh of individual cover costs ₹13,500–27,500 a year at 50 and ₹32,000–48,000 at 61. Costs rise with age and with any loading for a declared condition.
Should I add parents to my family floater?
No. A separate policy for parents is almost always better, because a floater is priced on the eldest member's age and one parent's claim can use up the family's shared cover.
Which is better for parents, HDFC ERGO or Star Health?
HDFC ERGO, on the published numbers. HDFC ERGO settles 97.8% of claims and draws 8.3 complaints per 10,000 claims; Star Health settles 89.3% and draws 53.9 (IRDAI data, three-year weighted average, latest as of March 2026). On plans, Optima Secure Plus carries no co-pay and no upper entry age, while Star Red Carpet closes entry at 75 and takes 30% of every claim.
Is there a maximum age to buy health insurance for parents?
Not on most mainstream plans. Since the IRDAI Master Circular on Health Insurance Business of 29 May 2024 removed the maximum entry age cap, Optima Secure Plus, Activ One, Care Supreme and Golden Shield set no upper entry age and ReAssure 3.0 takes entrants to 99, though underwriting still applies. Niva Bupa Senior First and Star Red Carpet close entry at 75.
Is Ayushman Bharat PM-JAY enough for parents over 70?
No, but it is worth enrolling. Since the Union Cabinet decision of 11 September 2024, PM-JAY covers everyone aged 70 and above, irrespective of income, up to ₹5 lakh a year on a family basis, and private policyholders remain eligible. A retail plan still adds a higher sum insured and the insurer's own hospital network.
Sources
- IRDAI (Insurance Products) Regulations, 2024, effective 1 April 2024: the 36-month cap on pre-existing-disease waits
- IRDAI Master Circular on Health Insurance Business, 29 May 2024: irdai.gov.in, read 24 October 2026
- IRDAI Master Circular on Protection of Policyholders' Interests, 5 September 2024: irdai.gov.in, read 24 October 2026
- Plan terms: each insurer's own prospectus, policy wording or customer information sheet, read in October 2026, with UINs under the plan table above
- Claim and complaint ratios: IRDAI published data, weighted average of the last three financial years, latest available as of March 2026
- Premiums: nyvo premium database, 720 quotes, April 2026
- Ayushman Bharat PM-JAY: Union Cabinet decision, Press Information Bureau, 11 September 2024; pmjay.gov.in
- Income-tax Act, 2025, section 126: incometaxindia.gov.in, read 24 October 2026
Disclaimer: Educational content only, not individual financial advice. Premiums, plan features and waiting periods are indicative and change; always read the policy wording and prospectus before buying. nyvo is an IRDAI-registered Corporate Agent (Composite), Licence No. CA1085.
16+ years in financial services. Former investment banker at Bank of America, Kotak Investment Banking, and SBICaps, and ex-CFO of slice. Founder of nyvo and Principal Officer – IRDAI Certified.