First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
Medical Inflation in India: 13% to 14% a Year
Medical inflation in India runs at 13% to 14% a year. A ₹5 lakh surgery today costs about ₹9.2 lakh to ₹9.6 lakh in five years. Here's why health insurance is essential.
Written by Kshitij JainUpdated nyvo insurance Services LLP, IRDAI Corporate Agent (Composite) CA1085Salaried advisors, no commission-based ranking
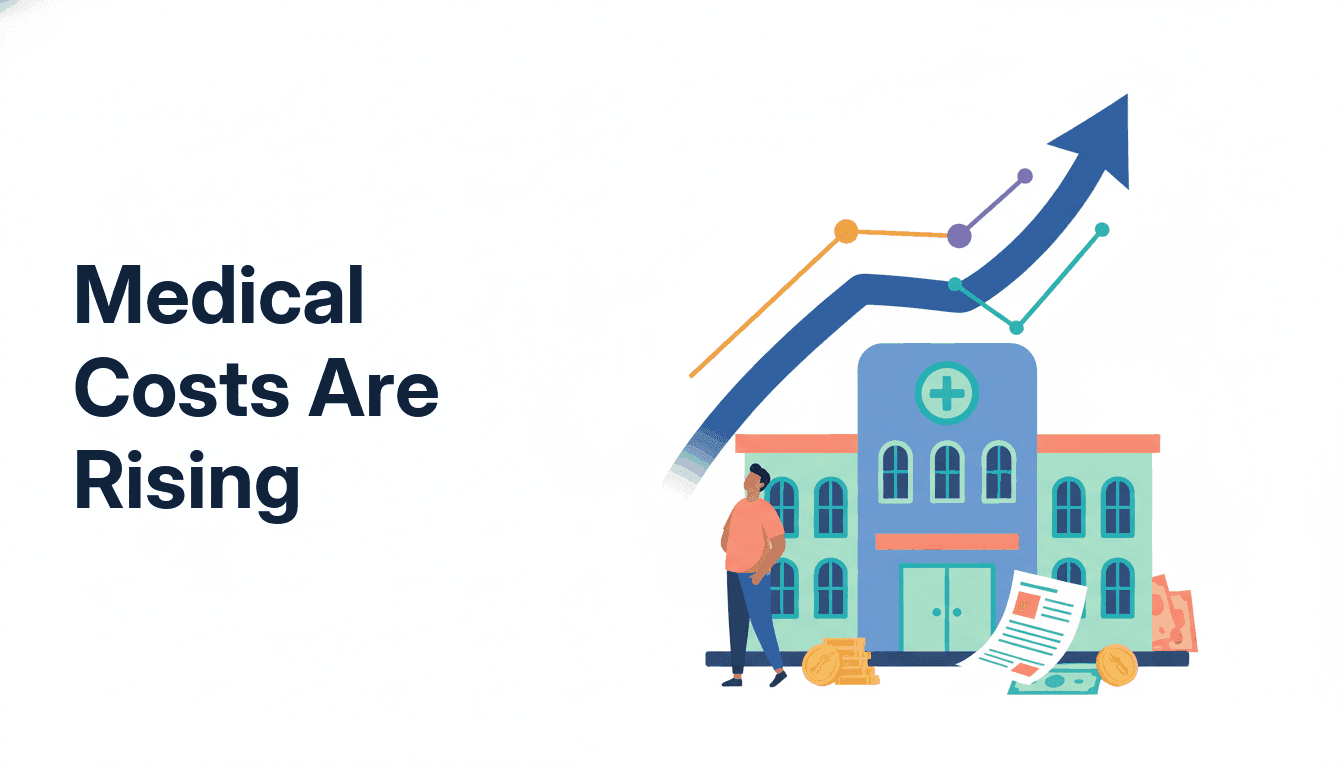
Medical inflation in India is 13% to 14% per year-your healthcare costs roughly double every five to six years. At those rates, a ₹5 lakh surgery today will cost ₹9.2 lakh to ₹9.6 lakh in 5 years and ₹31.3 lakh to ₹35.7 lakh in 15 years. Without adequate health insurance, a single hospitalization can wipe out years of savings. Health insurance isn't a "nice to have"-it's financial survival.
Quick checklist
- Reality: Medical costs in India grow at 13% to 14% annually (vs 5-6% general inflation).
- Impact: Treatment costs roughly double every five to six years.
- Protection: Adequate health insurance is the only practical hedge.
- Action: Review your sum insured annually; what was enough 3 years ago isn't enough today.
Medical inflation in India: The numbers
Historical medical inflation rates
| Year | Medical Inflation | General Inflation |
|---|---|---|
| 2019 | 7.1% | 4.8% |
| 2020 | 5.0% | 6.2% |
| 2021 | 8.4% | 5.1% |
| 2022 | 14.3% | 6.7% |
| 2023 | 14.0% | 5.4% |
| 2024 | 12% | 5-6% |
| 2025 (projected) | 13% | 4.2% |
Sources: Milliman, Measuring medical inflation in India, 8 April 2026, which puts the medical trend at 12% in 2024 and a projected 13% for 2025 against general inflation of 4.2%, and Milliman India Health Trends for the earlier years.
Key insight: Medical inflation runs at 2-3x the rate of general inflation. Your salary increases don't keep pace.
What drives medical inflation in India?
| Factor | Impact |
|---|---|
| Advanced technology | New treatments, equipment, and drugs cost more |
| Hospital infrastructure | Premium facilities charge premium prices |
| Doctor specialization | Super-specialists command higher fees |
| Drug costs | Patented medications, imported equipment |
| Land & construction | Hospital real estate costs in metros |
| Staff salaries | Medical professionals' pay increasing |
| Defensive medicine | More tests to avoid liability |
| Lifestyle diseases | Diabetes, heart disease becoming common |
Real hospitalization costs in 2024
Common procedures (metro city estimates)
| Procedure | Cost Range (₹) | 5 Years Ago |
|---|---|---|
| Appendectomy | 80,000–2,00,000 | 50,000–1,20,000 |
| C-section delivery | 1,00,000–3,00,000 | 60,000–1,80,000 |
| Angioplasty (two stents) | 2,50,000–5,00,000 | 1,50,000–3,00,000 |
| Bypass surgery | 1,20,000–4,40,000 | – |
| Knee replacement | 1,50,000–2,30,000 | – |
| Cancer treatment (total) | 10,00,000–30,00,000+ | 6,00,000–18,00,000 |
| ICU per day | 25,000–75,000 | 15,000–45,000 |
Source: nyvo research, September 2026. Metro-city estimates at 2024 prices. The knee replacement and bypass rows are the exception: they are the India ranges published by Yashoda Hospitals (read July 2026), one hospital group's list with no five-year-old figures, and the same ranges our guide to what insurance pays for common surgeries uses.
Hospital room charges (per day)
| Room Type | Metro Tier-1 | Tier-2 Cities |
|---|---|---|
| General ward | 3,000–6,000 | 1,500–3,000 |
| Semi-private | 6,000–12,000 | 3,000–6,000 |
| Private room | 12,000–25,000 | 6,000–12,000 |
| Deluxe/Suite | 25,000–50,000+ | 12,000–25,000 |
Source: nyvo research, September 2026. Per-day charges at 2024 prices.
The compounding problem: Cost projection
₹5 lakh treatment today becomes:
| Years from now | At 14% inflation | At 13% inflation | At 10% inflation |
|---|---|---|---|
| 5 years | ₹9.6 lakh | ₹9.2 lakh | ₹8.1 lakh |
| 10 years | ₹18.5 lakh | ₹17.0 lakh | ₹13.0 lakh |
| 15 years | ₹35.7 lakh | ₹31.3 lakh | ₹20.9 lakh |
| 20 years | ₹68.7 lakh | ₹57.6 lakh | ₹33.6 lakh |
| 25 years | ₹1.32 crore | ₹1.06 crore | ₹54.2 lakh |
Each cell is ₹5 lakh compounded annually at the stated rate, rounded.
Reality check: Your parents' ₹2 lakh policy from 2005 is essentially worthless today for any major hospitalization.
To run the projection for your own treatment cost and timeline, use our medical inflation calculator.
Why savings alone can't protect you
The math doesn't work
| Scenario | Amount |
|---|---|
| Annual savings | ₹3,00,000 |
| Years to save ₹10 lakh | 3.3 years |
| Probability of hospitalization in 3 years | Significant |
| Cost of single cardiac event | ₹5-15 lakh |
The problem: Medical emergencies don't wait for your savings to accumulate.
Opportunity cost
Money spent on medical bills could have been:
- Emergency fund for other needs
- Child's education fund
- Retirement corpus
- Home down payment
Health insurance preserves your wealth by transferring catastrophic risk to the insurer.
Is your current coverage adequate?
Warning signs your sum insured is too low
- Policy is more than 3 years old with same sum insured
- Sum insured is less than ₹10 lakh for family
- You live in a metro city
- Family has members above 50 years
- Any chronic conditions in family
Recommended minimum sum insured (2024)
| Family profile | Minimum SI | Recommended SI |
|---|---|---|
| Young couple (metros) | ₹10 lakh | ₹15-25 lakh |
| Family with kids (metros) | ₹15 lakh | ₹25-50 lakh |
| Family with parents (metros) | ₹25 lakh | ₹50 lakh+ |
| Senior citizens | ₹10 lakh | ₹15-25 lakh |
Related: How Much Health Cover Do You Need?
The smart approach: Base + Super Top-up
Instead of buying one expensive policy, consider:
| Component | Sum Insured | Approximate Premium |
|---|---|---|
| Base policy | ₹10 lakh | ₹15,000-25,000/year |
| Super top-up (₹10L deductible) | ₹50 lakh | ₹5,000-10,000/year |
| Total coverage | ₹60 lakh | ₹20,000-35,000/year |
This structure gives you 6x the coverage at reasonable premium.
Related: Base vs Super Top-up Explained
Corporate insurance is not enough
| Corporate Cover | Reality |
|---|---|
| "I have office insurance" | Ends when you leave/retire |
| "₹5 lakh family cover" | One hospitalization can exhaust it |
| "Free, so why buy more?" | You're uninsured when you need it most |
The gap: Corporate policies have sub-limits, room rent caps, and disappear when employment ends – often when you're older and premiums are higher.
Related: Corporate vs Personal Health Insurance
Annual review: Adjust for inflation
Every year, ask yourself:
- Has sum insured grown with medical inflation? (Should grow ~10-15% annually)
- Are room rent limits still realistic for good hospitals?
- Is family floater still adequate or should members have separate policies?
- Are parents covered adequately?
- Should I add a super top-up?
Red flags in renewal:
- Premium increased but sum insured stayed same
- Co-pay or sub-limits introduced
- Network hospitals reduced
- Waiting periods reset
Action steps
If you have no health insurance:
- Get quotes today – premiums only increase with age
- Start with minimum ₹10-15 lakh sum insured
- Add super top-up for catastrophic coverage
- Don't wait for "better time"-there isn't one
If you have existing insurance:
- Review sum insured against current costs
- Check room rent limits
- Verify sub-limits and exclusions
- Consider adding super top-up
- Don't let corporate cover create false security
FAQs
Why is medical inflation higher than general inflation?
Healthcare involves advancing technology, specialized professionals, imported equipment, increasing lifestyle diseases, and premium hospital infrastructure – all of which drive costs faster than everyday goods.
How much sum insured do I need in 2024?
For a family in metro cities, minimum ₹15-25 lakh. Families with elderly members or chronic conditions should consider ₹50 lakh+ through combination of base + super top-up plans.
Is ₹5 lakh health insurance enough?
In 2024, ₹5 lakh is barely sufficient for one moderate hospitalization in a metro city. It's a starting point but not adequate protection. Consider supplementing with a super top-up.
How often should I increase my sum insured?
Review annually. Ideally, sum insured should grow by 10-15% each year to keep pace with medical inflation. Many policies offer this as cumulative bonus.
Can I rely on savings instead of health insurance?
Financially unwise. A single major hospitalization (cancer, cardiac, accident) can cost ₹10-30 lakh – potentially wiping out years of savings. Insurance transfers this catastrophic risk.
What about government health schemes like Ayushman Bharat?
Ayushman Bharat covers up to ₹5 lakh a year for families that meet its socio-economic criteria, and, since 29 October 2024, every Indian aged 70 and above regardless of income (Union Cabinet decision of 11 September 2024). Below 70, if you're reading this, you likely don't qualify, and ₹5 lakh is insufficient for private hospital care.
Why do health insurance premiums keep increasing?
Due to medical inflation, increasing claim costs, and your own aging. Premium increases of 10-15% annually are normal. Locking in a policy when young results in lower lifetime costs.
Is medical inflation the same across India?
No. Metro cities (Mumbai, Delhi, Bangalore) have higher costs than tier-2/3 cities. But tier-2 cities are catching up fast as quality healthcare expands.
How do I protect against future medical inflation?
Buy adequate coverage now while premiums are lower, choose a policy with a cumulative bonus, add a super top-up for catastrophic costs, and review your coverage every year.
Disclaimer: Cost estimates are indicative based on industry data. Actual costs vary by hospital, city, and treatment complexity. Review your specific needs with a qualified advisor.
Related Guides
Our editorial principles
- Salaried advisors, not commission-linked: we focus on clarity and suitability, not product hype.
- No spam: we don't sell your data; we keep advice simple and actionable.
- Claims-first: policy features are evaluated by how they behave during claims.
- Education-first: this content is for informational purposes only.
Book a call for advice on the best policy for you and your family
A salaried, IRDAI-certified nyvo advisor will look at your cover, flag the gaps that matter, and tell you plainly what to fix. No commission, no pressure.
A first in India
Buy policy from nyvo insurance with Claim Support Guarantee, otherwise money back.
Alumni of IIT Delhi and IIM Ahmedabad. Former consultant at BCG and part of the strategy team of slice. Founder of nyvo and IRDAI Certified Insurance Advisor.