First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
Term Insurance Without ITR: First Job, Self-Employed and Gig Work
Buying term insurance without an income tax return is harder, not impossible. The income documents insurers list for first-jobbers, the self-employed and gig workers, how to raise cover later, and what to do when the insurer offers less than you asked for.
Written by Kshitij JainReviewed by Harsh SoniUpdated nyvo insurance Services LLP, IRDAI Corporate Agent (Composite) CA1085Salaried advisors, no commission-based ranking
Can you buy term insurance without an ITR?
Yes. No income tax return does not mean no term insurance; it means the insurer sizes your cover on the income proof you do have. IRDAI's Master Circular on Protection of Policyholders' Interests (5 September 2024) lets a life insurer ask for income details "along with proof of income to ascertain the premium paying capacity". It does not require an ITR. Which documents count, and how much cover they support, each insurer sets in its own Board-approved underwriting policy.
That opens three routes. A salaried first-jobber can apply with payslips and salary credits before their first tax return. A self-employed buyer or gig worker can use bank statements, TDS records and business documents. And anyone who gets less cover than they asked for can take it now and add more later. Individual life insurance has carried no GST since 22 September 2025, so the premium you are quoted is the premium you pay.
Why do insurers ask for income proof?
Term cover replaces income, so the insurer checks that there is income to replace and that you can pay the premium. Tata AIA's own guide puts it plainly: the insurer uses your income proof to judge your financial worth and whether you can keep paying. Income tax returns appear on every one of the six insurers' document lists we read, which is why many buyers assume an ITR is required.
Many earners do not have one yet, or file late:
- First-jobbers, who may not yet have filed a return for the tax year in which they started work.
- Gig workers. NITI Aayog estimated that 77 lakh (7.7 million) workers were engaged in the gig economy in 2020-21 ("India's Booming Gig and Platform Economy", policy brief, June 2022).
- Creators, freelancers and traders, whose income arrives unevenly.
- Homemakers, who earn no income of their own.
- Family-business members who draw income without being on a payroll.
For each of these, the answer is the right document set and a realistic cover amount, not going without.
Buying term insurance in your first job: what counts as income proof?
You can apply in your first months with an appointment letter, payslips and the salary credits in your bank account; you do not have to wait for your first ITR. For someone who has just joined, HDFC Life lists an appointment letter with the latest salary, and Canara HSBC Life an appointment letter with the latest month's salary slip. Most insurers' lists also include 3 months of salary slips and 3 to 6 months of bank statements, which a new joiner builds up within the first half-year.
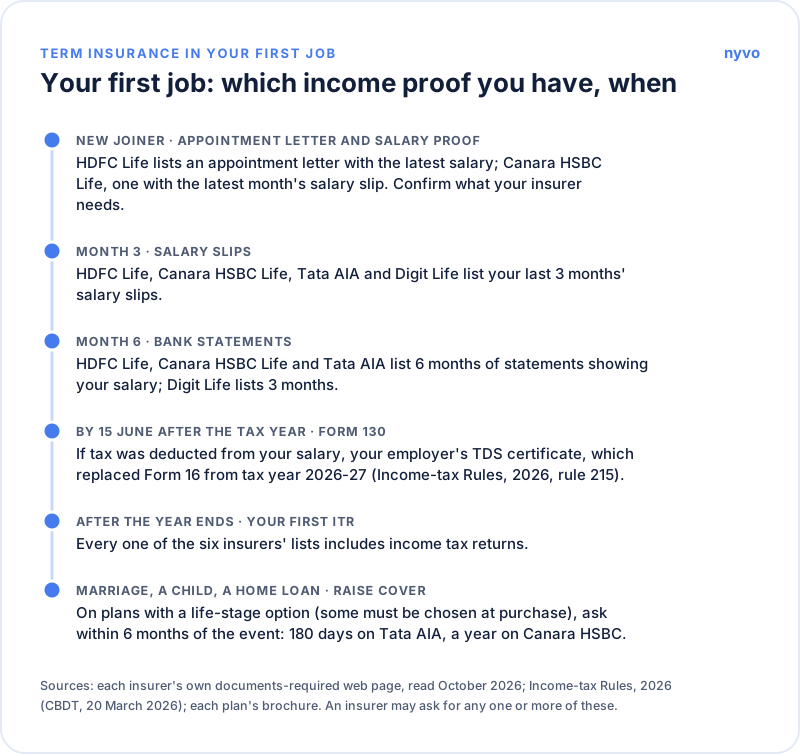
What each insurer lists on its own website for salaried buyers:
| Insurer (page date) | Documents it lists for salaried buyers | If you have just joined |
|---|---|---|
| HDFC Life (28 Nov 2025) | Form 16 for the latest financial year; 6 months of salary-account statements; 3 months of salary slips with bank statements; the previous year's ITR with income computation | An appointment letter with the latest salary |
| Canara HSBC Life (6 Aug 2026) | 6 months of bank statements showing salary; 3 months of salary slips; 2 years of ITRs; recent Form 16 | An appointment letter with the latest month's salary slip, for a fresher or a recent job change |
| Tata AIA Life | 3 months of salary slips; 3 years of ITRs; recent Form 16; 6 months of bank statements showing salary; a recent salary certificate from the employer; a CA certificate under 2 months old; Form 26AS | Not stated |
| Digit Life (12 Oct 2026) | 3 months of salary slips; recent Form 16; 3 months of bank statements; 2 years of ITRs; "may request one or more" | Not stated |
| Bajaj Life (19 Feb 2026) | Recent salary slips; bank statements showing salary; Form 16; 3 years of ITRs | Not stated |
| Kotak Life (1 Sep 2025) | Salary slips; ITRs; Form 16; bank statements showing regular income; an employer certificate or letter confirming income | Not stated |
Source: each insurer's own "documents required" web page, read October 2026. These are lists of what an insurer may accept, not a set you must hand over in full; the underwriter decides which ones your application needs.
How much cover your income supports is each insurer's own rule. Kotak Life's guide says younger applicants may get up to 25 times their annual income, and older applicants a lower multiple; that multiple is applied to the income your documents prove.
When your Form 16 arrives. If tax was deducted from your salary, your employer's certificate of that tax is due by 15 June after the tax year ends. From tax year 2026-27 it is Form No. 130 under the Income-tax Rules, 2026 (rule 215); for 2025-26 and earlier years it is Form 16 under rule 31 of the Income-tax Rules, 1962. If you joined in, say, August 2026 and tax was deducted from your salary during tax year 2026-27, your employer's Form 130 is due by 15 June 2027, and your first tax return follows after the year ends. That can mean many months of waiting for documents your payslips already show.
Should you buy a smaller cover now and raise it later?
Usually yes: take the cover your current documents support, at today's age, and plan how to add to it. Several plans let you raise cover on marriage, a child or a home loan without starting a new policy. Some must be chosen at purchase, so decide before you buy. The alternative is a second policy later, underwritten on its own.
| Plan | Events and maximum increase | Conditions |
|---|---|---|
| HDFC Life Click 2 Protect Supreme Plus | First marriage 50% (up to ₹50 lakh); first and second child 25% each (up to ₹25 lakh); home loan 50% (up to ₹50 lakh); ₹1.5 crore in total | Chosen at purchase; under 45 at the event; standard life at inception; within 6 months; no underwriting at the time |
| ICICI Pru iProtect Smart Plus | Marriage 50%; first and second child 25% each; home loan 100% | Regular pay, Life or Life Plus; under 50 at the event; within 6 months; subject to underwriting |
| Tata AIA Maha Raksha Supreme Select | Marriage 50%; first and second child 25% each; home loan up to 100%, subject to the loan amount | Within 180 days; up to 4 increases; subject to underwriting |
| Bajaj Life eTouch II | Marriage, first and second child, a home loan or a child's education loan; up to 100% of the original cover in total | Chosen at purchase; before 45; within 6 months; underwriting at the time |
| Canara HSBC iSelect Smart360 | Marriage 50%; a child or a new house 25%; up to 3 times | Life Secure, regular pay, level cover; standard life at inception; within a year; no underwriting at the time |
Source: each plan's current brochure (HDFC Life UIN 101N189V03, ICICI Pru 105N205V07, Tata AIA 110N171V15, Bajaj Life 116N198V10, Canara HSBC 136N080V02). Each increase carries an extra premium at your age then.
A life-stage increase is the simpler route, because it needs no new application and, on HDFC Life and Canara HSBC, no fresh underwriting. A second policy is the fallback: it is assessed on your health and income at the time, so buy it before a new diagnosis makes it harder. Our guide on how much term cover you need sets the total to aim for.
The insurer offered less cover than you asked for: should you accept?
In most cases, accept it. A counter-offer means the insurer will issue a policy, but on different terms: a lower cover than you asked for, an extra premium, or both. Ask whether the cut was for income or for health, because the fix is different. Once the insurer has communicated its acceptance on the new terms, cover starts when it receives your premium, priced at today's age.
IRDAI sets the timetable. Under its Master Circular on Protection of Policyholders' Interests (5 September 2024), the insurer must ask for any further documents in one go within 7 days of receiving your proposal, decide within 7 days of getting them, and give its reasons if it does not accept. Premium is payable only after the insurer tells you it accepts, and cover starts when the premium is received. A counter-offer is one of the outcomes insurers write into their own policy documents: LIC's Digi-Term policy document, for example, defines underwriting as the decision on accepting or rejecting cover and on applying a "suitable premium or modified terms".
| Accept the lower cover now | Wait and apply again later |
|---|---|
| Covered once the insurer has communicated acceptance and received the premium | No cover until a new policy is issued |
| Premium fixed at today's age | Premium rises with age: on the median of the five plans nyvo rates, each year of waiting adds about 2% in your late twenties (nyvo's premium data, May 2026) |
| Add cover later through a life-stage option or a second policy | Reapply once you have Form 16 or Form 130 and an ITR |
| Your health is assessed as it is today | Your health is assessed again when you reapply; a new diagnosis by then can mean an extra premium or a decline |
Three things to do before you decide:
- Ask what would change the decision. If the cover was cut for income, ask which document would support more: a salary certificate, 6 months of statements, or your Form 16 (Form No. 130 from tax year 2026-27).
- Never inflate your income or skip a question to get more cover. In the first three years of a life policy, a material misstatement lets the insurer question the policy and refuse the claim (Section 45 of the Insurance Act, 1938).
- If you paid an amount with your application, remember that it is not acceptance and does not start cover. If you decide not to take the offer, ask the insurer in writing to refund what you paid.
Self-employed, freelancers and gig workers: which documents work?
Insurers list tax returns first, and business records and bank statements alongside them. Digit Life lists, for freelancers and gig workers, 3 years of ITRs, client invoices, 6 months of bank statements and professional receipts. HDFC Life asks a self-employed buyer for any one of 2 years of ITRs with income computation, or 3 years of audited balance sheets and profit and loss accounts. Bajaj Life adds GST returns where applicable.
Documents that help when you have no ITR, or a thin one:
- Form 26AS and your Annual Information Statement (AIS). From AY 2023-24, Form 26AS on the TRACES portal shows only tax deducted or collected at source; the AIS shows your other reported details (Income Tax Department, AIS FAQs). From tax year 2026-27 the Annual Information Statement is Form No. 168 (Income-tax Rules, 2026, rule 245). If a client deducted TDS on your payments, it shows here. Tata AIA lists Form 26AS among the income proof it accepts.
- Bank statements with steady credits. Digit Life lists 6 months for freelancers and gig workers.
- TDS certificates from clients: Form 16A, which becomes Form No. 131 from tax year 2026-27 (Income-tax Rules, 2026).
- GST returns, if you are registered (Bajaj Life lists them for the self-employed and Digit Life for business owners).
- A chartered accountant's certificate of your income. Tata AIA lists one not more than 2 months old.
- Invoices and contracts for freelancers (Digit Life lists client invoices and professional receipts).
Put the whole set together before you apply, so the insurer can ask for anything missing in one go.
Can a homemaker buy term insurance without income proof?
Yes, usually sized against the earning spouse's income. HDFC Life lists the spouse's income proof for a housewife's application, together with documents such as 6 months of her own bank statements. Some plans also offer joint-life or spouse options; read how each one works before relying on it, because some start the spouse's cover only after the earner's death. Our guide to term insurance for a homemaker covers the options.
When is a smaller plan still the right move?
If the highest cover an insurer will offer today is well below what your family needs, you have three options.
Option A: take the smaller plan now. Cover what you can today, then add to it as your documents improve. Some cover for the next two years is worth more than none.
Option B: split the cover across two insurers. Each policy is underwritten separately, and each insurer asks about cover you already hold, so disclose the other policy on each application.
Option C: file your ITR and apply again. If the income is genuinely there, file a return even at a low bracket, build a year of tax and bank records, and reapply. Keep in mind that every year of waiting raises the premium and leaves you uncovered meanwhile.
More cover later comes from an option built into your plan, such as a life-stage increase, or from a new policy.
Frequently Asked Questions
Can I buy term insurance in India without filing ITR?
Yes. IRDAI lets insurers ask for proof of income, not specifically an ITR, and insurers list salary slips, bank statements, Form 16, employer certificates, CA certificates and Form 26AS among the documents they may accept. Expect the cover to be sized on what your documents show.
Can I buy term insurance in my first job with only payslips?
Often, but payslips alone are not guaranteed to be enough. HDFC Life lists an appointment letter with the latest salary for a recent joiner, Canara HSBC Life an appointment letter with the latest month's salary slip, and most insurers list 3 months of salary slips and 3 to 6 months of bank statements. The insurer decides what your application needs.
When will I get Form 16 in my first job?
By 15 June after the tax year ends, if tax was deducted from your salary that year. From tax year 2026-27 the employer's salary TDS certificate is Form No. 130 under the Income-tax Rules, 2026; for 2025-26 and earlier it is Form 16. If you joined in August 2026 and tax was deducted from your salary in tax year 2026-27, your first one is due by 15 June 2027.
The insurer offered me less cover than I applied for. Should I accept?
Usually yes. Once the insurer has communicated acceptance and received the premium, you are covered at today's age, and you can add cover later through a life-stage option or a second policy. Ask the insurer which document would have supported more cover.
How fast must an insurer decide on my term insurance proposal?
Within 7 days of receiving the information it needs, under IRDAI's Master Circular on Protection of Policyholders' Interests (5 September 2024). It must ask for any extra documents in one go within 7 days of your proposal, and give reasons if it does not accept.
Can I increase my term cover later?
Yes, on plans with a life-stage option, such as HDFC Life Click 2 Protect Supreme Plus, ICICI Pru iProtect Smart Plus, Tata AIA Maha Raksha Supreme Select, Bajaj Life eTouch II and Canara HSBC iSelect Smart360, after events such as marriage, a child or a home loan. Otherwise, buy a second policy, which is underwritten on its own.
Which documents replace ITR for term insurance?
Insurers list bank statements, salary slips, Form 16, employer income certificates, CA certificates and Form 26AS. For freelancers and gig workers, Digit Life also lists client invoices and professional receipts, and Bajaj Life lists GST returns for the self-employed.
Can a homemaker buy term insurance?
Yes, usually sized against the earning spouse's income, whose income proof the insurer asks for. HDFC Life, for example, lists the spouse's income proof plus 6 months of the homemaker's own bank statements.
Related guides:
Sources:
- IRDAI Master Circular on Protection of Policyholders' Interests, 2024, Ref IRDAI/PP&GR/CIR/MISC/117/9/2024, 5 September 2024 (proposal form, payment of premium, processing of proposals)
- IRDAI Master Circular on Life Insurance Products, Ref IRDAI/ACTL/MSTCIR/MISC/89/6/2024, 12 June 2024 (Board-approved underwriting policy)
- Income-tax Rules, 2026, CBDT notification G.S.R. 198(E), 20 March 2026, rule 215 and Forms 130 and 131; CBDT Circular No. 12 of 2021 (Form 16 under rule 31 of the Income-tax Rules, 1962)
- Income Tax Department, FAQs on the Annual Information Statement (Form 26AS from AY 2023-24); Income-tax Rules, 2026, rule 245 (Annual Information Statement in Form No. 168)
- NITI Aayog, "India's Booming Gig and Platform Economy", policy brief, June 2022
- Insurers' own documents-required pages: HDFC Life, Canara HSBC Life, Tata AIA Life, Digit Life, Bajaj Life, Kotak Life (read October 2026)
- Plan brochures: HDFC Life Click 2 Protect Supreme Plus (101N189V03), ICICI Pru iProtect Smart Plus (105N205V07), Tata AIA Maha Raksha Supreme Select (110N171V15), Bajaj Life eTouch II (116N198V10), Canara HSBC iSelect Smart360 (136N080V02)
Term insurance without an ITR at a glance
| What IRDAI allows | An insurer may ask for income details with proof of income to judge your ability to pay the premium (IRDAI Master Circular on Protection of Policyholders' Interests, 5 September 2024) |
|---|---|
| Who sets the documents | Each insurer, under its Board-approved underwriting policy (IRDAI Master Circular on Life Insurance Products, 12 June 2024) |
| Salaried, what insurers list | Salary slips (usually 3 months), salary-account statements (3 to 6 months), Form 16 or Form 130, ITRs (insurers' own web pages, read October 2026) |
| Just joined | HDFC Life lists an appointment letter with the latest salary; Canara HSBC Life, one with the latest month's salary slip (insurers' web pages, read October 2026) |
| Employer's TDS certificate | Form 130 from tax year 2026-27, due by 15 June after a tax year in which tax was deducted from your salary (Income-tax Rules, 2026, rule 215, notified 20 March 2026) |
| Decision on your proposal | Within 7 days of the insurer receiving the information it needs; reasons given if it does not accept (IRDAI Master Circular, 5 September 2024) |
| Raising cover later | Ask within 6 months of the event on HDFC Life Supreme Plus, ICICI Pru iProtect Smart Plus and Bajaj Life eTouch II; 180 days on Tata AIA Maha Raksha Supreme Select; 1 year on Canara HSBC iSelect Smart360 (plan brochures, read October 2026) |
Document lists are what each insurer publishes on its own website; the insurer can ask for any one or more of them, and for others.
Book a call for advice on the best policy for you and your family
A salaried, IRDAI-certified nyvo advisor will look at your cover, flag the gaps that matter, and tell you plainly what to fix. No commission, no pressure.
A first in India
Buy policy from nyvo insurance with Claim Support Guarantee, otherwise money back.
Alumni of IIT Delhi and IIM Ahmedabad. Former consultant at BCG and part of the strategy team of slice. Founder of nyvo and IRDAI Certified Insurance Advisor.