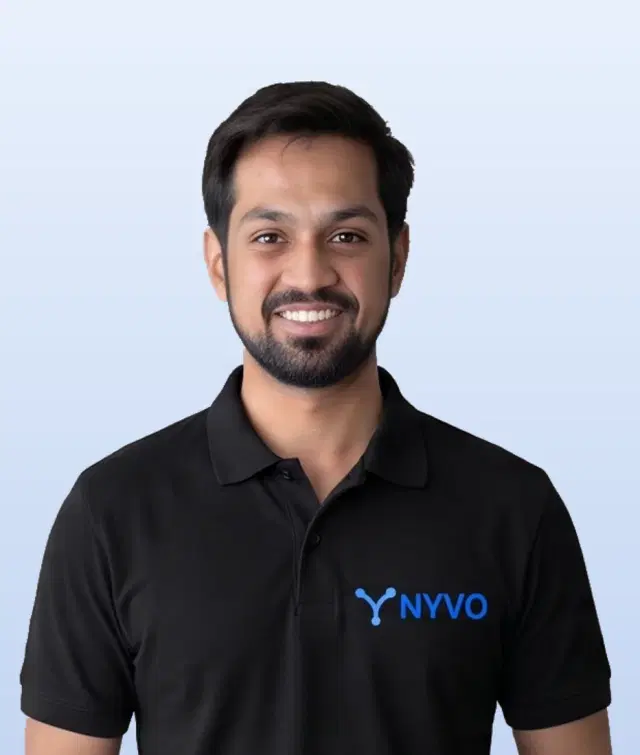
Kshitij Jain
Founder
Kshitij brings the rigour of strategy consulting to the way Indian families should think about insurance. B.Tech in Chemical Engineering from IIT Delhi. MBA from IIM Ahmedabad as Institute Scholar (top 5%). Cleared all three levels of the CFA examination. He worked at Boston Consulting Group (BCG) and Essex Lake Group, then on the strategy team at slice, where he developed one of India's earliest need-based insurance mapping systems. At nyvo, he leads the analytical framework behind plan recommendations and the methodology that makes claim reliability measurable rather than marketed.
Why nyvo
When Kshitij's elder brother moved abroad, his parents lost their corporate health insurance overnight. Searching for a replacement, he found a market full of confusing jargon, conflicting reviews, and sales-driven recommendations. Kshitij wanted a solution that offered transparent, fact-based advice – not marketing pitches. nyvo is the answer he and Harsh built together.
Education
Credentials
- CFA – All 3 Levels Cleared (CFA Institute)
- Institute Scholar (top 5%), IIM Ahmedabad
- B.Tech Chemical Engineering, IIT Delhi
- IRDAI Certified Insurance Advisor
Career
- Foundernyvo insurance Services LLP · 2025–Present
- Strategy & Partnershipsslice · Fintech Unicorn
- ConsultantEssex Lake Group
- ConsultantBoston Consulting Group (BCG)
Writes about
In the press
Reporting that quotes Kshitij.
- Insurance reforms: Why claims matter more than distribution costs
 18 October 2026
Mint on why claims settlement and grievance redress matter as much as IRDAI's distribution reforms, quoting nyvo founder Kshitij Jain on wrongful claim rejections and on controlling hospital costs instead of a mandatory 10% co-pay.
- Uncapped coverage: Is your health policy really ‘unlimited’?12 October 2026
Mint on unlimited health cover from Niva Bupa, Care, ICICI Lombard and HDFC ERGO, priced on nyvo's premium data, quoting nyvo founder Kshitij Jain on what the costliest treatments run to.
- Irdai’s distribution overhaul: Will it make insurance cheaper, curb mis-selling?27 September 2026
Mint on IRDAI's proposed commission caps and mis-selling safeguards, quoting nyvo founder Kshitij Jain on claim settlement ratios by amount and verified accounts.
Articles by Kshitij Jain
50 articles on insurance, claims, and Indian family financial planning.
Health Insurance
Standard health policies make you wait up to three years before they'll pay for a pre-existing condition like diabetes or hypertension. A growing set of plans and add-ons cover those conditions from day one, or after a short wait, in exchange for a higher premium and full disclosure. Here is how day-1 PED cover works, who genuinely needs it, what it costs, and how to tell a real day-1 benefit from marketing language.
No health plan you buy yourself covers childbirth from day one. These are the shortest maternity waits we've found, 9 and 12 months, and what each plan actually pays for a delivery.
Mental illness has been mandatory in every Indian health policy since 2022. See what is actually covered (IPD, OPD, day care), what is not, and how to claim it.
After your health policy has run continuously for five years, the insurer largely loses the right to reject a claim on the grounds of non-disclosure or misrepresentation, except for proven fraud. This is the moratorium period, and IRDAI shortened it from eight years to five in 2024. Here is what the moratorium protects, what it does not, and why it is the strongest argument for buying early and never letting a policy lapse.
The doctor visits, scans and blood tests before your admission, and the follow-ups, medicines and physiotherapy after discharge, are usually covered by your health policy. Most families never claim them because they don't know the cover exists or they bin the receipts. Here is how pre- and post-hospitalisation cover works, the typical 30 and 60-day windows, what's in and out, and how to claim the part of your bill everyone leaves on the table.
You got an online quote for ₹12,400 and the final premium came to ₹16,900 – same plan, same sum insured. That gap is 'loading', an extra charge the insurer adds when it assesses you as higher risk. Here is exactly why insurers load premiums, how much they typically add for diabetes, blood pressure, high BMI and tobacco, and the proven ways to bring it down or remove it.
Term Insurance
What does ₹1 crore term cover actually cost? Real 2026 premiums by age and gender (30-year-old man: ₹8,856 to ₹10,440 a year) and what waiting really costs.
Axis Max Life Smart Term Plan Plus vs ICICI Pru iProtect Smart Plus, compared on terminal illness, who picks the payout, premium returns and claim record.
₹1 crore term insurance starts at ₹738/month for a healthy 30-year-old man, ₹628 for a woman. Compare the 5 best plans on price, claim record and payouts.
The best ₹2 crore term insurance plans for 2026, compared on claim settlement ratio, premium by age, and riders. See who actually needs ₹2Cr cover and what it costs.
₹3 crore term insurance compared across top plans: terminal illness caps, rider limits, underwriting, and whether to buy one policy or split the cover.
How to buy ₹5 crore or more of term insurance: plans with no upper limit, how insurers decide large covers, terminal illness caps and protecting the payout.
Who ₹50 lakh term insurance suits, which top-rated plans sell it, what changes below ₹1 crore of cover, and how to raise your cover later.
Term insurance claim process: documents needed, a step-by-step filing guide, and IRDAI's settlement deadline of 15 days from intimation, or 45 if investigated.
Complete term insurance guide for India: how much cover you need, ideal tenure, best riders, honest disclosure tips, and claim checklist.
HDFC Life vs ICICI Prudential term insurance: Click 2 Protect Supreme Plus against iProtect Smart Plus on real premiums, claim settlement ratio, riders and payout options.
Calculate term cover: add loans, 10–15 years of household expenses and goals, then subtract liquid assets and existing life cover. Worksheet and calculator.
Joint life term insurance covers both spouses under 1 policy at 10-15% lower cost. Joint vs separate plans compared with real premiums.
Axis Max Life vs HDFC Life term insurance: Smart Term Plan Plus against Click 2 Protect Supreme Plus on real premiums, claim settlement ratio, riders and payout options.
Nominee vs legal heir in term insurance: who gets the payout, how to avoid disputes, and when to update your nomination after life events.
Term insurance in India for NRIs: who can buy, eligibility by country of residence, NRE/NRO premium payment, documents and how a claim is settled from abroad.
Return of premium (ROP) term insurance costs about twice as much as plain term on regular pay, on Axis Max Life's own rates. What the refund is really worth.
Term insurance riders explained: accidental death, critical illness, waiver of premium. Compare costs, claim triggers, and which riders are worth adding.
Smokers pay a separate, higher term insurance rate in India. How insurers' own forms define a smoker, whether occasional or social smoking counts, how the nicotine test works, whether you can move to non-smoker rates later, and why a wrong answer is the bigger risk.
Tata AIA Sampoorna Raksha Promise vs HDFC Life Click 2 Protect Supreme Plus, compared on terminal illness, payouts, riders, premium breaks and claim record.
Term insurance tax benefits: up to ₹1.5L deduction under Section 80C (section 123 of the Income-tax Act, 2025, from tax year 2026-27), old regime only. Death benefit tax-free under Section 10(10D) in both regimes. Save ₹3,000-5,000/year.
How to choose the age your term cover ends: match it to your dependants and your loans, pick the cover amount at the same time, and see what a cover to 75 or 85 really buys.
Term insurance after 40 in India: higher premiums, medical tests, what changes, and how to get the best plan if you haven't bought term cover yet.
Term insurance for homemakers: why housewives need life insurance, how much cover, best plans, and how to calculate the economic value of a homemaker.
Can your father or mother still buy term insurance at 54 or 59? Which plans take a new buyer at 50, 55, 60 and 65, how far the cover can run, what the insurer will ask for, why it costs so much more, and when term cover is the wrong answer.
Buying term insurance without an income tax return is harder, not impossible. The income documents insurers list for first-jobbers, the self-employed and gig workers, how to raise cover later, and what to do when the insurer offers less than you asked for.
The difference between term insurance and health insurance: what each pays, when and to whom, what a claim needs, the tax rules, what both cost at 30, what to buy first, and what a term plus health combo really is.
Term vs ULIP vs endowment: term gives ₹1 crore cover at ₹800/month while ULIPs cost 5-10x more. Why pure term + separate investing wins.
Term insurance with diabetes, BP, or thyroid is possible with full disclosure. Expect 15-30% premium loading. Non-disclosure risks claim rejection.
Term insurance in plain words: what it pays, why a plain plan pays nothing if you outlive it while refund versions cost more, what ₹1 crore costs at 30, the tax rules and who needs it.
Women pay about 15% less than men for the same term cover. How much cover working women and homemakers need, with real premiums and plans for 2026.
Claims
The hospital bill was ₹3.2 lakh, your sum insured was ₹10 lakh, and the insurer paid only ₹2.4 lakh – leaving you to settle ₹80,000 at the discharge counter. Those deductions are rarely random. Here are the seven reasons insurers deduct from an approved cashless claim, which ones are legitimate, and how to challenge the ones that are wrong.
Cashless pre-authorisation rejected at hospital admission? Stay calm. This 60-minute action plan walks you through every step – getting denial in writing, escalating to the insurer hotline, switching to reimbursement track, and when to call nyvo claims support.
The claim was approved and the amount sanctioned – and then it sat for three weeks because the nominee's name on the policy didn't match her PAN, or the bank account failed penny-drop verification. Documentation mismatches are the most avoidable reason a settled claim doesn't reach the family. Here is every mismatch that stalls a payout and how to fix each one fast.
Your father needed hospital-level treatment but couldn't be moved, or no bed was available, so the doctor treated him at home. Most families assume insurance won't pay for that. It often will, under a clause called domiciliary hospitalisation. Here is what it covers, the two conditions that unlock it, what insurers exclude, and exactly how to document a home-treatment claim so it isn't rejected.
File an HDFC ERGO claim the right way: cashless and Cashless Everywhere process, reimbursement, helpline numbers, document checklist, and how to escalate a delay.
Health insurance claim rejected? 90% of rejections are one of 7 patterns: non-disclosure, waiting period, sub-limit, document gap, exclusion, room-rent cap, procedural. Fix each.
Hospital bills in India are routinely inflated 15-40% on phantom charges, double-billed consumables, and excess room rent. This step-by-step guide shows you how to audit a hospital bill line by line, what charges to challenge, how to negotiate before discharge, and how the audit affects your insurance claim settlement.
Your insurer approved cashless treatment, yet the admission desk is demanding a ₹50,000 deposit before they will admit your parent. This happens more often than families expect, and it is usually legal. Here is why it happens, when you can refuse, how much you should actually pay, and exactly how to get the deposit back at discharge.
Your parent has just been admitted to hospital. The next 24 hours decide whether the cashless claim goes through smoothly or your family ends up paying lakhs out of pocket. Here's a hour-by-hour action plan – what to do, who to call, what to bring, and the mistakes that cost families money.
Term insurance claim process in India: who files, what documents are needed, investigation timelines, and what nominees should expect step by step.
General
Corporate vs personal health insurance: why corporate cover alone isn't enough and how to build complete family protection.
Insurance checklist for startup founders in India: personal health, term, key-man, group insurance for employees, and D&O liability cover.
Medical inflation in India runs at 13% to 14% a year. A ₹5 lakh surgery today costs about ₹9.2 lakh to ₹9.6 lakh in five years. Here's why health insurance is essential.
Most Indian adult children avoid the parents-and-insurance conversation because it feels morbid, presumptuous, or financially intrusive. Here's how to actually have it – three opening lines that work, the four pieces of information you genuinely need, and what to do when your parents say no.
Talk to Kshitij or the nyvo advisory team
Free 30-minute consultation. No spam, no pressure, no commission-driven recommendations.