First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
Unlimited Sum Insured Health Insurance: What You Actually Get
Unlimited sum insured, a 100% bonus every year, 2X cover from day one and unlimited restoration: what each one means in the policy wording, what it switches off, and how a ₹10 lakh policy grows over ten years under six plans' own rules.
"Unlimited" in Indian health insurance means one of four different things, and none of them is unlimited money for every bill. An Unlimited sum insured option removes the annual ceiling. A once-in-a-lifetime add-on pays one claim without a limit. Unlimited restoration refills your base cover for later claims in the same year. And an uncapped bonus grows your cover every year with no ceiling. Each comes with conditions, written into the policy wording.
This guide reads those conditions plan by plan, then charts how a ₹10 lakh policy grows over ten years under six plans' own rules, with and without a claim.
What does "unlimited" mean in a health insurance policy?
"Unlimited" in a health policy refers to one of four features: an Unlimited sum insured option with no annual ceiling, an add-on that pays one claim of unlimited value in the life of the policy, restoration that refills the base cover an unlimited number of times a year, or a bonus with no upper cap. They work differently and are often confused in a sales conversation.
| What "unlimited" refers to | What the wording promises | What it does not do | Examples in their own wording |
|---|---|---|---|
| Unlimited sum insured option | No annual ceiling on the sum insured | Switches off the bonus and restoration on each of the plans listed | Niva Bupa ReAssure 3.0, Care Ultimate Care, ICICI Lombard Elevate, Star Super Star |
| One claim of unlimited value | One claim in the life of the policy paid without a sum insured limit | Ends once used; still subject to sub-limits, co-pays and deductibles | Care Supreme's Unlimited Care, ICICI Lombard Elevate's Infinite Care, both paid add-ons |
| Unlimited restoration | Refills the base cover any number of times in a policy year | Each refill is capped at the base cover; some plans skip the first claim; unused refills lapse at renewal | HDFC ERGO Optima Secure Plus, Care Supreme, Aditya Birla Activ One Max |
| Uncapped bonus | Adds to the cover every year with no ceiling | Paid add-on versions are forfeited if you stop paying for them | Built into Optima Secure Plus; a paid add-on on Elevate, Care Ultimate Care and Star Super Star |
Sources: Niva Bupa ReAssure 3.0 prospectus, UIN NBHHLIP26047V012526; Care Ultimate Care prospectus, UIN CHIHLIP26058V022526; ICICI Lombard Elevate prospectus, UIN ICIHLIP27057V062627; Star Super Star policy wording, UIN SHAHLIP27049V022627; Care Supreme prospectus, UIN CHIHLIP27061V032627; HDFC ERGO my:Optima Secure prospectus, UIN HDFHLIP26058V082526; Aditya Birla Activ One prospectus, UIN ADIHLIP24097V012324.
Does an Unlimited sum insured option mean no limits at all?
No. An Unlimited sum insured option removes the annual ceiling on cover, but on every plan we read it also switches off the features that work by adding to a defined sum insured, such as the yearly bonus and restoration. Waiting periods, exclusions and the plan's room-rent and co-pay rules still apply to every claim.
What each plan's own wording switches off on its Unlimited option:
- Niva Bupa ReAssure 3.0 is sold at ₹5 lakh, ₹10 lakh or Unlimited. Booster+ and ReAssure Forever are not offered on the Unlimited option (prospectus, UIN NBHHLIP26047V012526).
- Care Ultimate Care sells sum insured from ₹5 lakh to ₹1 crore, or Unlimited. On the Unlimited option, the cumulative bonus, unlimited automatic recharge, Loyalty Boost, Infinity Bonus, Unlimited Care, Tenure Multiplier and several other benefits do not apply (prospectus, UIN CHIHLIP26058V022526).
- ICICI Lombard Elevate sets a minimum annual sum insured of ₹5 lakh and a maximum of "Unlimited". The Loyalty Bonus, the Reset Benefit, the Power Booster add-on and the Infinite Care add-on are not available on unlimited policies (prospectus and policy wording, UIN ICIHLIP27057V062627).
- Star Super Star offers an Unlimited sum insured, on which the cumulative bonus, automatic restoration and the Super Star Bonus add-on are not applicable (policy wording, UIN SHAHLIP27049V022627).
The trade is headroom for growth. A defined sum insured with an uncapped or large bonus can grow well past most single bills over a decade, as the chart below shows, while an Unlimited option has no ceiling from day one but never grows or refills.
Is a 100% bonus every year real?
Yes, on some plans. Of the plans read here, only HDFC ERGO Optima Secure Plus builds in 100% a year with no ceiling, whether or not you claim. Niva Bupa ReAssure 3.0 adds the base cover you did not use, up to 1000% of base, and Aditya Birla Activ One Max adds 100% a year up to 500%. On several other plans, a 100% yearly bonus is a paid add-on.
| Plan and bonus | Added each year | Ceiling | What a claim does | Built in or paid add-on |
|---|---|---|---|---|
| HDFC ERGO Optima Secure Plus: Infinite Benefit | 100% of the expiring year's base sum insured, from the end of year 1 | None | Nothing: added irrespective of claims | Built in |
| Niva Bupa ReAssure 3.0: Booster+ | The part of the base sum insured left unused that year | 10 times the base (1000%) | Shrinks that year's addition by what the claim took from the base | Built in; not on the Unlimited option |
| Aditya Birla Activ One Max: Super Credit | 100% of base | 500% of base, and ₹3 crore | Nothing: added irrespective of claims | Built in |
| Care Supreme: Cumulative Bonus | 50% of the sum insured | 100% | Does not reduce it | Built in |
| Care Supreme: Cumulative Bonus Super | A further 100% of the sum insured | 500% | No impact on accrual | Paid add-on; forfeited if not renewed |
| ICICI Lombard Elevate: Loyalty Bonus | 20% | 100% | Does not reduce it | Built in; not on unlimited policies |
| ICICI Lombard Elevate: Power Booster | 100% of the expiring or renewed annual sum insured, whichever is lower | None stated; it can accumulate up to an unlimited sum insured | Added irrespective of claims | Paid add-on; reduced to zero if you opt out |
| Tata AIG MediCare Premier: Cumulative Bonus option | 50% after each claim-free year | 100% | Cut by 50% of the sum insured in the following year | Chosen instead of a renewal premium discount |
| Care Ultimate Care: Infinity Bonus | 100% of base, on top of the base cumulative bonus | None stated ("for unlimited period") | Added irrespective of claims | Paid add-on; forfeited if not renewed |
| Star Super Star: Super Star Bonus | 100% of the expiring or renewed annual sum insured, whichever is lower | None stated; it can accumulate up to an unlimited sum insured | Added irrespective of claims | Paid add-on; reduced to zero if you opt out |
Sources: each plan's prospectus or policy wording as listed above, plus Tata AIG MediCare Premier policy wording, UIN TATHLIP26052V052526. Care Supreme's base bonus of 50% a year to 100%, and the 500% version being the paid Cumulative Bonus Super, match nyvo's policy database.
Two words in this table decide most of its value. A bonus added "irrespective of claims" keeps growing in the years you use the policy. A no-claim bonus, like Tata AIG's, stops or falls back in those years, and a carry-forward like ReAssure's Booster+ adds less. Our no-claim bonus guide covers how the claim-dependent kind works.
Is ₹5 lakh with 2X Secure really ₹15 lakh?
Not in the first year. On HDFC ERGO's base Optima Secure plan, the Secure Benefit adds 100% of the base sum insured, so ₹5 lakh is ₹10 lakh of cover in year 1. The Plus Benefit then adds 50% of base a year, to a ceiling of 100%, so the cover reaches ₹12.5 lakh in year 2 and ₹15 lakh from year 3, whether or not you claim (my:Optima Secure prospectus, UIN HDFHLIP26058V082526).
| Policy year | Base sum insured | Secure Benefit | Plus Benefit | Cover for the year |
|---|---|---|---|---|
| 1 | ₹5 lakh | ₹5 lakh | ₹0 | ₹10 lakh |
| 2 | ₹5 lakh | ₹5 lakh | ₹2.5 lakh | ₹12.5 lakh |
| 3 onwards | ₹5 lakh | ₹5 lakh | ₹5 lakh | ₹15 lakh |
Base Optima Secure plan at ₹5 lakh, renewed without a break, before any restoration. Optima Secure Plus, a different plan in the same filing, replaces the Plus Benefit with the uncapped Infinite Benefit.
Three conditions in the wording shape how the Secure Benefit pays. It is applied once in each policy year, and any unused part does not carry forward. It can be used for any number of claims in that year. And it becomes available only once the base sum insured is used up (my:Optima Secure prospectus, UIN HDFHLIP26058V082526). For a full comparison of the two plans, see Optima Secure vs Optima Secure Plus.
How does ₹10 lakh grow over 10 years under each plan's rules?
On a ₹10 lakh base renewed without a break, HDFC ERGO Optima Secure Plus reaches ₹110 lakh of cover in year 10, Niva Bupa ReAssure 3.0 ₹100 lakh, Aditya Birla Activ One Max ₹60 lakh, and Care Supreme, Tata AIG MediCare Premier and ICICI Lombard Elevate ₹20 lakh each. One ₹6 lakh claim in year 3 cuts ReAssure 3.0's year 10 to ₹94 lakh and changes none of the other year-10 figures (arithmetic on each plan's own wording, rules listed below the table).
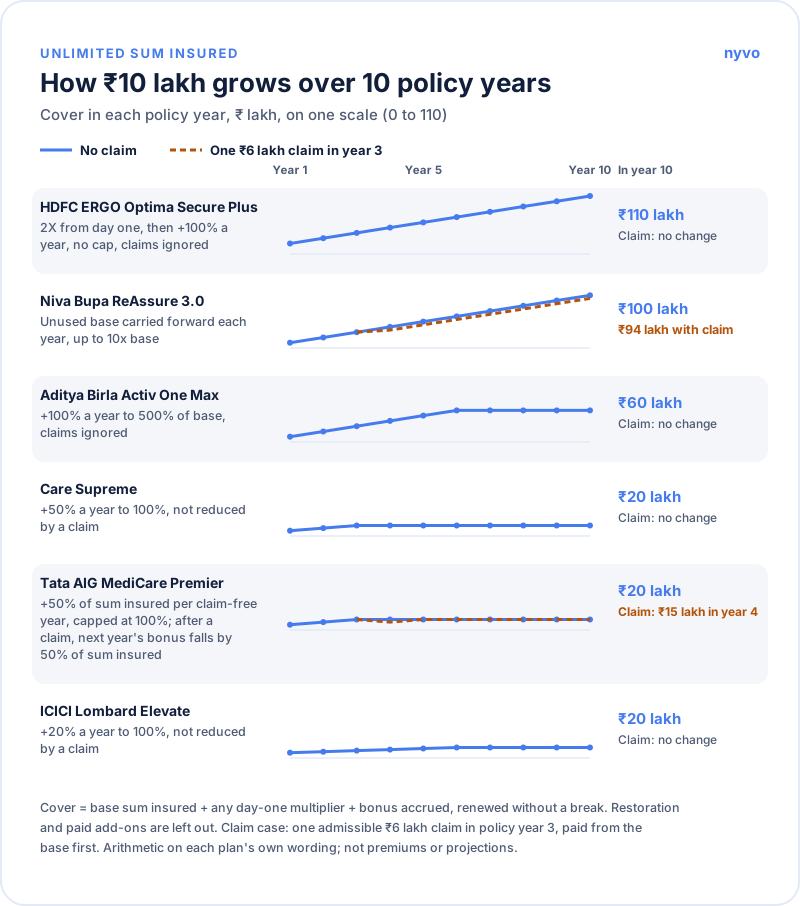
| Plan, ₹10 lakh base | Year 1 | Year 3 | Year 4 | Year 5 | Year 10 | Year 10 after a ₹6 lakh claim in year 3 |
|---|---|---|---|---|---|---|
| HDFC ERGO Optima Secure Plus | ₹20 lakh | ₹40 lakh | ₹50 lakh | ₹60 lakh | ₹110 lakh | ₹110 lakh |
| Niva Bupa ReAssure 3.0 | ₹10 lakh | ₹30 lakh | ₹40 lakh | ₹50 lakh | ₹100 lakh | ₹94 lakh |
| Aditya Birla Activ One Max | ₹10 lakh | ₹30 lakh | ₹40 lakh | ₹50 lakh | ₹60 lakh | ₹60 lakh |
| Care Supreme | ₹10 lakh | ₹20 lakh | ₹20 lakh | ₹20 lakh | ₹20 lakh | ₹20 lakh |
| Tata AIG MediCare Premier | ₹10 lakh | ₹20 lakh | ₹20 lakh | ₹20 lakh | ₹20 lakh | ₹20 lakh |
| ICICI Lombard Elevate | ₹10 lakh | ₹14 lakh | ₹16 lakh | ₹18 lakh | ₹20 lakh | ₹20 lakh |
The rules applied, each from the plan's own document, with nothing assumed beyond them:
- What "cover" means here: the base sum insured, plus any day-one multiplier, plus the bonus accrued, available in that policy year. Restoration is left out, because it depends on claims already made in the year and some plans do not apply it to a first claim. No add-ons are included.
- The claim: one admissible ₹6 lakh claim in policy year 3, paid from the base sum insured first, with the policy renewed on time every year.
- Optima Secure Plus: Secure Benefit of 100% of base from day one; Infinite Benefit of 100% of the expiring year's base at the end of each policy year, irrespective of claims, with no maximum (my:Optima Secure prospectus, UIN HDFHLIP26058V082526).
- ReAssure 3.0: Booster+ carries forward the base sum insured left unused in a year, up to 10 times the base. After the year-3 claim, ₹4 lakh carries forward instead of ₹10 lakh, so years 4 to 10 of this illustration are each ₹6 lakh lower. With no further claims, the no-claim case reaches the ₹110 lakh ceiling (base plus 10 times base) in year 11 and the claim case catches up in year 12 (prospectus, UIN NBHHLIP26047V012526).
- Activ One Max: Super Credit of 100% of base a year, irrespective of claims, up to 500% of base (₹50 lakh here, below the ₹3 crore cap) (Activ One prospectus and MAX policy wording, UIN ADIHLIP24097V012324).
- Care Supreme: Cumulative Bonus of 50% a year up to 100%, which "shall not reduce in case of claim" (prospectus, UIN CHIHLIP27061V032627).
- MediCare Premier, Cumulative Bonus option: 50% after each claim-free year up to 100%; after a claim, the bonus is cut by 50% of the sum insured the following year. So year 4 falls to ₹15 lakh and year 5 is back at ₹20 lakh (policy wording, UIN TATHLIP26052V052526).
- Elevate: Loyalty Bonus of 20% at the end of each policy year, irrespective of a claim, up to 100% (prospectus, UIN ICIHLIP27057V062627).
Star Super Star is not charted: its wording reduces the cumulative bonus "to the extent of utilized portion", and how a claim splits between the sum insured and the bonus is not spelled out clearly enough to chart. Plans with a paid bonus add-on are charted without it.
What the chart shows is the shape of each rule, not a recommendation. A bonus that ignores claims protects you in exactly the years you are likely to claim, and the gap between a plan that keeps adding 100% a year and one that stops at 100% keeps widening every year after the capped bonus stops. What it does not show is the premium for each plan, which nyvo does not compare here.
What does unlimited restoration not do?
Unlimited restoration refills your base cover any number of times in a policy year; it does not make one claim unlimited. On HDFC ERGO's wording, restored cover "can only be used to pay subsequent claims", and a single claim can never exceed the base sum insured plus the Secure Benefit and bonus (my:Optima Secure prospectus, UIN HDFHLIP26058V082526). Where another plan lets a refill help a claim, each refill is capped at the base sum insured. Unused restoration lapses at the end of the policy year.
When the refill switches on also differs by plan:
- ICICI Lombard Elevate: the Reset Benefit "will not be triggered for the first claim made during the Policy Year" (policy wording, UIN ICIHLIP27057V062627).
- Aditya Birla Activ One Max: Super Reload does not pay on the first claim in the life of the policy. From the second claim on, it reloads the base sum insured whenever the base and Super Credit are used up or are not enough for a claim, paying up to the base sum insured on any one claim (policy wording, UIN ADIHLIP24097V012324).
- Niva Bupa ReAssure 3.0: ReAssure Forever is triggered by the first paid claim in the life of the policy and then lasts for life if you renew without a break, each refill capped at the base sum insured; it does not apply on the Unlimited option (prospectus, UIN NBHHLIP26047V012526).
- Care Supreme: Unlimited Automatic Recharge reinstates the base sum insured once claims have used up the sum insured, for the same or a different illness, and the bonuses are not counted when it is calculated (prospectus, UIN CHIHLIP27061V032627).
Our restoration benefit guide compares the trigger rules across more plans.
Which kind of "unlimited" is worth having?
For most families, the features worth paying for are a bonus that a claim cannot touch and restoration that covers the same illness, on a defined sum insured large enough for one major admission. An Unlimited sum insured option suits a buyer who wants no ceiling from day one and accepts that the cover will not grow or refill. A one-claim unlimited add-on is a single safety valve, used once.
- If you expect to claim in the next ten years, a bonus added irrespective of claims keeps your cover growing through those years.
- If one very large bill is the worry, compare an Unlimited option, a one-claim add-on and a high sum insured plan or a super top-up on the same quote.
- If you are buying for parents, check whether these options are open to them at all, then compare with a super top-up above their existing policy.
- Before you pay for an add-on, read what happens if you drop it: Care Supreme's Cumulative Bonus Super is forfeited, and Elevate's Power Booster and Star's Super Star Bonus fall to zero.
Mint's report of 12 October 2026, "Uncapped coverage: Is your health policy really ‘unlimited’?" by Aprajita Sharma, looked at unlimited health cover from Niva Bupa, Care, ICICI Lombard and HDFC ERGO, priced on nyvo's premium data, and quoted nyvo founder Kshitij Jain. See nyvo in the press.
If you want the wording of the plan in front of you read against your own family's needs, an IRDAI-certified nyvo advisor will go through it with you. Salaried, not commission-led. Health and term only. IRDAI Corporate Agent (Composite), licence CA1085.
FAQs
Is unlimited sum insured health insurance really unlimited?
Only the annual ceiling is unlimited. On Niva Bupa ReAssure 3.0, Care Ultimate Care, ICICI Lombard Elevate and Star Super Star, the Unlimited option switches off the bonus and restoration, and waiting periods, exclusions, room-rent and co-pay rules still apply to each claim (each plan's prospectus or wording).
Which health insurance plan gives a 100% bonus every year?
HDFC ERGO Optima Secure Plus builds in 100% of base cover a year with no ceiling, irrespective of claims. Aditya Birla Activ One Max adds 100% a year up to 500%, and Niva Bupa ReAssure 3.0 carries forward the unused base cover up to 1000%. On Care Supreme, ICICI Lombard Elevate, Care Ultimate Care and Star Super Star, a 100% yearly bonus is a paid add-on.
Is ₹5 lakh with 2X Secure Benefit the same as ₹15 lakh of cover?
Not in year 1. On HDFC ERGO's base Optima Secure plan, ₹5 lakh is ₹10 lakh in year 1 with the Secure Benefit, ₹12.5 lakh in year 2 and ₹15 lakh from year 3 once the Plus Benefit reaches 100% (my:Optima Secure prospectus, UIN HDFHLIP26058V082526).
Does a claim reduce the bonus on these plans?
It depends on the plan. Optima Secure Plus, Activ One Max, Care Supreme and ICICI Lombard Elevate add their bonus irrespective of claims. ReAssure 3.0 carries forward only the base cover you did not use, and Tata AIG MediCare Premier's cumulative bonus is cut by 50% of the sum insured the year after a claim.
Can unlimited restoration pay for one very large bill?
No. Restoration refills the base cover during the policy year, and each refill is capped at the base sum insured. On HDFC ERGO's wording, restored cover pays only later claims and a single claim can never exceed the base sum insured plus the Secure Benefit and bonus.
What is a one-claim unlimited add-on?
It is an optional benefit that pays one claim in the life of the policy without a sum insured limit. Care Supreme's Unlimited Care can be opted only at inception and must be kept for five policy years, and ICICI Lombard Elevate's Infinite Care can be opted only at inception or, on a one-year policy, at the first renewal; both end once used.
Related guides:
Sources:
- HDFC ERGO my:Optima Secure prospectus, UIN HDFHLIP26058V082526 (Optima Secure and Optima Secure Plus)
- Niva Bupa ReAssure 3.0 prospectus, UIN NBHHLIP26047V012526
- Aditya Birla Activ One prospectus and Activ One MAX policy wording, UIN ADIHLIP24097V012324
- Care Supreme prospectus, UIN CHIHLIP27061V032627
- Care Ultimate Care prospectus, UIN CHIHLIP26058V022526
- ICICI Lombard Elevate prospectus, UIN ICIHLIP27057V062627
- Tata AIG MediCare Premier policy wording, UIN TATHLIP26052V052526
- Star Super Star policy wording, UIN SHAHLIP27049V022627
- Mint, "Uncapped coverage: Is your health policy really ‘unlimited’?", 12 October 2026, as listed on nyvo's press page
Unlimited cover at a glance
| Unlimited sum insured option | Niva Bupa ReAssure 3.0, Care Ultimate Care, ICICI Lombard Elevate and Star Super Star; each switches off its bonus and restoration on that option (each plan's prospectus or policy wording, read October 2026) |
|---|---|
| One claim of unlimited value | Care Supreme's Unlimited Care and ICICI Lombard Elevate's Infinite Care, once in the life of the policy, as paid add-ons (Care Supreme prospectus, UIN CHIHLIP27061V032627; Elevate prospectus, UIN ICIHLIP27057V062627; October 2026) |
| Bonus with no ceiling, built in | HDFC ERGO Optima Secure Plus, 100% of base cover a year whether or not you claim (my:Optima Secure prospectus, UIN HDFHLIP26058V082526, October 2026) |
| Largest capped bonus, built in | Niva Bupa ReAssure 3.0 carries forward the base cover a year leaves unused, up to 1000% of base (prospectus, UIN NBHHLIP26047V012526, October 2026) |
| 2X from day one | Optima Secure Plus's Secure Benefit adds 100% of base cover, usable once a policy year after the base is used up (my:Optima Secure prospectus, UIN HDFHLIP26058V082526, October 2026) |
| ₹10 lakh after nine renewals | ₹110 lakh on Optima Secure Plus, ₹100 lakh on ReAssure 3.0 (₹94 lakh after one ₹6 lakh claim in year 3), ₹60 lakh on Activ One Max, ₹20 lakh on Care Supreme, Tata AIG MediCare Premier and ICICI Lombard Elevate (arithmetic on each plan's wording, October 2026) |
Cover figures are arithmetic on each plan's own bonus and multiplier rules for a ₹10 lakh base renewed without a break, with restoration left out. They are not premiums or projections.
Book a call for advice on the best policy for you and your family
A salaried, IRDAI-certified nyvo advisor will look at your cover, flag the gaps that matter, and tell you plainly what to fix. No commission, no pressure.
A first in India
Buy policy from nyvo insurance with Claim Support Guarantee, otherwise money back.
16+ years in financial services. Former investment banker at Bank of America, Kotak Investment Banking, and SBICaps, and ex-CFO of slice. Founder of nyvo and Principal Officer – IRDAI Certified.