First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
ACKO Health Insurance Review: What ACKO Platinum Covers and What It Leaves Out
ACKO Platinum read from ACKO's own policy wording: what it covers, what it leaves out, which ACKO product it belongs to, and how it compares with HDFC ERGO Optima Secure Plus and Care Supreme on the terms that decide a claim.
ACKO Platinum is a plan within ACKO General Insurance's retail health product, not a separate product with its own UIN. On ACKO's own Health III (Platinum) policy wording (UIN ACKHLIP27040V012627), it pays room rent and ICU at actual cost with no cap, pays consumables and other non-payable items, waives the 30-day initial wait and the specified-illness waits, except cataract and non-infectious arthropathies for anyone insured above 50, and covers 60 days before and 180 days after a hospital stay. It has no restoration benefit and no bonus, excludes maternity, and leaves the pre-existing disease wait to underwriting. ACKO General settles 95.4% of claims (IRDAI data, three-year weighted average, latest as of March 2026).
nyvo holds no ACKO premium quotes, so this review gives no ACKO price. What it does show, from ACKO's own documents, is what the plan includes and leaves out, which is where any difference in price sits.
What is ACKO Platinum: a separate policy or a plan?
ACKO Platinum is a plan, a fixed bundle of options inside ACKO's filed health product, and not a product with its own UIN. ACKO's downloads page carries three Platinum wordings, "ACKO Health III (Platinum)", "(Platinum Lite)" and "(Platinum Super Top-up)", all printed with ACKO Health III's UIN, ACKHLIP27040V012627. ACKO's own marketing page says Platinum Lite is also known as the ACKO Standard Plan.
ACKO's own pages do not agree on which filing Platinum sits under. Its disclaimer page, read on 19 October 2026, says "ACKO Platinum & Platinum Lite plans are sold under Product: Acko Health II", giving UIN ACKHLIP26036V012526, and that ACKO Health II replaced the older Acko Personal Health Policy (UIN ACKHLIP25035V022425). The ACKO Health II documents on ACKO's downloads page now carry a different UIN, ACKHLIP27042V022627. The practical answer is the same either way: read the product name and UIN printed on your own policy schedule, and the wording filed under that UIN. This review uses the Health III Platinum wording, the only one ACKO publishes under Platinum's own name.
How Platinum differs from Platinum Lite
The two Health III wordings are identical except for two benefits. Platinum adds the Reduction in Specific Illness Waiting Period (Essential), which removes the specified-illness waits except cataract and non-infectious arthropathies for insured people above 50, and the Initial 30 Days Waiting Period Waiver. Platinum Lite keeps both waits, for the number of months printed on the schedule. Apart from those two benefits, and a mention of an inflation-protect amount in Platinum's definition of total sum insured, the two wordings read the same, from the uncapped room rent to the maternity exclusion.
What does ACKO Platinum cover?
ACKO Platinum covers hospitalisation with no room-rent cap, consumables and other non-payable items, and the usual list of day care, domiciliary, AYUSH, organ-donor and modern treatments, each up to the sum insured. Its strongest terms are on day one: the 30-day initial wait is waived, and so are the specified-illness waits, except cataract and non-infectious arthropathies for anyone insured above 50. Its gaps are restoration, a bonus, and maternity.
| Term | ACKO Platinum, from the Health III (Platinum) wording |
|---|---|
| Room rent and ICU | "We cover actual room rent and ICU charges without any capping" (section 2.2) |
| Pre and post hospitalisation | 60 days before, 180 days after (2.4) |
| Consumables and non-payables | Paid: consumables are listed among in-patient expenses (2.1), and the Waiver of Non-payable Medical Expenses is built in (2.12) |
| Road ambulance and emergency evacuation in India | Up to the sum insured (2.5, 2.6) |
| Day care, domiciliary, AYUSH, organ donor, modern treatments | Covered up to the sum insured (2.3, 2.7, 2.8, 2.10, 2.11) |
| Specified-illness wait | Waived, except cataract and arthropathies (excluding infectious causes) for anyone insured above 50 (2.13) |
| Initial 30-day wait | Waived (2.15) |
| Pre-existing disease wait | The number of months printed on your schedule (3.1.1) |
| Restoration and bonus | Neither appears in the Platinum wording |
| Maternity | Excluded: childbirth, miscarriage other than after an accident, and medical termination; ectopic pregnancy excepted (3.1.16) |
| Extra, outside the sum insured | Preventive health check-up and unlimited doctor-on-call consultations (2.14, 2.17) |
Two clauses deserve a second read. The wording lists an individual deductible (2.16), so check whether your schedule shows one. And among the permanent exclusions it lists "oral/oropharynx/respiratory cancer excluded in tobacco user" (3.2.1), so a tobacco user should ask ACKO in writing how that applies before buying. ACKO is not alone here: Care Supreme's prospectus (UIN CHIHLIP27061V032627) excludes any illness attributable to tobacco use.
Other terms from ACKO Health III's prospectus: cover from 91 days of age with no maximum entry age and no cover-ceasing age; individual or floater policies for a wide list of relatives, including parents, parents-in-law, grandparents and siblings; terms of 1, 2 or 3 years; and sum insured options from ₹3 lakh to ₹10 crore plus an unlimited option. Which of those ACKO offers on Platinum is shown when you buy; the prospectus notes that not every plan is available at all times.
How does ACKO Platinum compare with Optima Secure Plus and Care Supreme?
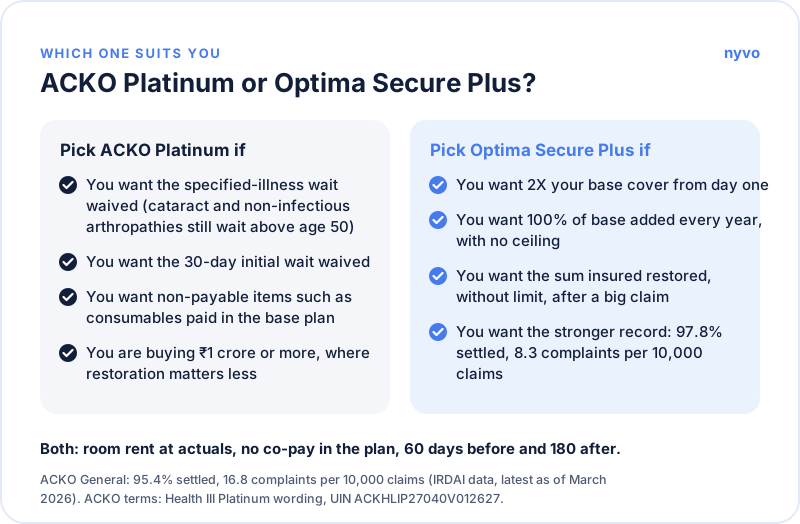
ACKO Platinum matches HDFC ERGO Optima Secure Plus and Care Supreme on room rent, co-payment and pre- and post-hospitalisation, beats both on day-one waits, and falls behind both on restoration and on a bonus. On claim record, ACKO General sits below HDFC ERGO and Care Health on settlement, and between them on complaints.
| Term | ACKO Platinum | HDFC ERGO Optima Secure Plus | Care Supreme |
|---|---|---|---|
| Room rent | Actual cost, no cap | At actuals, no cap | No cap |
| Co-payment | None in the Platinum wording | None | None in the base plan |
| Consumables | Paid (non-payables waiver built in) | Listed consumables paid (Protect Benefit) | Not in the base plan; Claim Shield is a paid extra |
| Pre and post hospitalisation | 60 / 180 days | 60 / 180 days | 60 / 180 days |
| Restoration | None | Unlimited, automatic | Unlimited, same illness included |
| Cover growth | No bonus; any inflation-protect amount shows on your schedule | 2X the base from day one; 100% of base added every year, no ceiling | 50% a year, up to 100% |
| Specified-illness wait | Waived, except cataract and non-infectious arthropathies above 50 | 24 months | 24 months |
| Initial 30-day wait | Waived | 30 days | 30 days |
| Pre-existing disease wait | Set by underwriting, on your schedule | 36 months | 36 months |
| Maternity | Excluded | Parenthood add-on, 2-year wait | Not covered |
| Claim settlement ratio | 95.4% | 97.8% | 96.0% |
| Complaints per 10,000 claims | 16.8 | 8.3 | 42.9 |
Sources: ACKO Health III (Platinum) policy wording, UIN ACKHLIP27040V012627. Optima Secure Plus and Care Supreme terms from each plan's policy wording as recorded in nyvo's policy database; Care Supreme's UIN CHIHLIP27061V032627 matches its live prospectus, and HDFC ERGO's live documents carry UIN HDFHLIP26058V082526. Claim ratios: IRDAI published data, three-year weighted average, latest available as of March 2026. ACKO's figures are ACKO General Insurance's, the health and general insurer, not ACKO Life's.
nyvo does not publish a hospital count for any of the three, because a national total says little about the hospitals near you. Check each insurer's cashless list for your city before you choose.
Why might ACKO quote less for the same sum insured?
nyvo holds no ACKO quotes, so we cannot confirm that ACKO is cheaper for your age and city. Where an ACKO Platinum quote does come in below Optima Secure Plus or Care Supreme for the same sum insured, the wordings show what the lower price leaves out: restoration, a bonus, and, against Optima Secure Plus, a maternity option. Against that, Platinum waives most of the waits the other two impose.
- No restoration. Optima Secure Plus and Care Supreme both refill the sum insured without limit within a year; ACKO Platinum's wording has no restore benefit. Our guide to the restoration benefit explains when a refill actually pays.
- No bonus. Optima Secure Plus starts at twice the base and adds 100% of the base every year; Care Supreme adds 50% a year to 100%. ACKO Platinum's wording has no bonus section. It names an Inflation Protect Sum Insured only in its definition of total sum insured, without setting the benefit out, and ACKO Health II's plan table lists inflation protect at 10% of the sum insured for Plan 1, the plan ACKO's disclaimer page ties to Platinum. Check your schedule for an inflation-protect amount: without one, the cover does not grow. Our guide to the no-claim bonus covers how each kind of bonus works.
- A pre-existing wait set by underwriting. ACKO's disclaimer page says "Coverage from day 1 is subject to disclosure of pre-existing conditions and underwriting". The wording leaves the wait to your schedule, within the 36-month maximum set by the IRDAI (Insurance Products) Regulations, 2024. Ask for that number in writing.
- Two zones for premium. Zone A is Delhi/NCR, Mumbai (with Navi Mumbai, Thane and Kalyan), Kolkata (with Howrah) and a list of other pincodes; Zone B is the rest of India. See how zone-based premiums work across insurers.
What Platinum includes as standard: the specified-illness waits waived, except cataract and non-infectious arthropathies above 50 (24 months on the other two), the 30-day initial wait waived (30 days on the other two), and non-payable items paid, which Optima Secure Plus also covers through its Protect Benefit and Care Supreme charges extra for as Claim Shield. Our guide to consumables shows why that matters on a real bill.
Is ACKO Platinum a good choice?
ACKO Platinum is a reasonable choice at a large sum insured, ₹1 crore or more, where one year's claims are less likely to use up the cover, so restoration and a bonus add less. There, its waived waits, with the over-50 exception, and paid consumables are real advantages. At ₹10 lakh to ₹25 lakh, where the cover has to grow to keep pace with bills, Optima Secure Plus's 2X from day one and 100% a year matter more.
The claim record belongs in the same decision. ACKO General settles 95.4% of claims, below HDFC ERGO's 97.8% and Care Health's 96.0%, and draws 16.8 complaints per 10,000 claims, more than HDFC ERGO's 8.3 and well below Care Health's 42.9 (IRDAI published data, three-year weighted average, latest available as of March 2026). See ACKO's claim settlement ratio and the complaint ratios of every health insurer.
Three checks before you buy ACKO Platinum:
- The UIN and product name on your schedule, and the wording filed under it.
- The pre-existing disease wait printed on your schedule, and any named-ailment exclusion, which the wording says overrides the standard waits.
- Whether a deductible appears on your schedule, given the wording's individual-deductible clause.
If you want to see where a very large or unlimited sum insured fits, our guide to unlimited sum insured plans compares them. For ACKO's servicing details, see ACKO health insurance.
FAQs
Is ACKO Platinum a separate health insurance policy?
No. Platinum is a plan within ACKO's filed health product. ACKO's downloads page carries the Platinum wording under ACKO Health III, UIN ACKHLIP27040V012627, while ACKO's disclaimer page says Platinum is sold under ACKO Health II, so check the UIN on your own schedule.
Does ACKO Platinum have a room rent limit?
No. The Platinum wording says ACKO covers actual room rent and ICU charges without any capping.
Does ACKO Platinum have a waiting period?
Only some. The 30-day initial wait is waived, and the specified-illness waits are waived except cataract and non-infectious arthropathies for anyone insured above 50. The pre-existing disease wait is set by underwriting and printed on your schedule, within the 36-month legal maximum.
Does ACKO Platinum cover consumables?
Yes. Consumables are listed among in-patient expenses, and the Waiver of Non-payable Medical Expenses is built into the Platinum wording, so items on ACKO's non-payable list are paid when they are medically necessary and the claim itself is admitted.
Does ACKO Platinum have restoration or a no-claim bonus?
Neither appears in the ACKO Health III Platinum wording. Optima Secure Plus and Care Supreme both include unlimited restoration and a bonus that adds cover each year.
Does ACKO health insurance cover maternity?
Not on Platinum. The wording excludes childbirth, miscarriage other than after an accident, and medical termination of pregnancy, with ectopic pregnancy as the exception.
What is ACKO's claim settlement ratio?
95.4%, with 16.8 complaints per 10,000 claims, for ACKO General Insurance (IRDAI published data, three-year weighted average, latest available as of March 2026). These are ACKO General's health figures, not ACKO Life's.
Why is ACKO health insurance cheaper?
nyvo holds no ACKO quotes, so we cannot confirm it is cheaper for you. Where it does quote lower, the Platinum wording has no restoration and no bonus, while Optima Secure Plus doubles cover from day one and adds 100% a year.
Can I buy ACKO Platinum for my parents?
Possibly. ACKO Health III's prospectus allows parents and parents-in-law and states no maximum entry age, but confirm that Platinum is offered for your parents on the quote you receive; availability and underwriting both apply. Cataract and non-infectious arthropathies still carry a wait for anyone insured above 50, and the pre-existing disease wait is set on the schedule.
Related guides:
Sources:
- ACKO Health III (Platinum) policy wording, ACKO Health III (Platinum Lite) policy wording and ACKO Health III prospectus, UIN ACKHLIP27040V012627, acko.com downloads page, read 19 October 2026
- ACKO Health II prospectus, UIN ACKHLIP27042V022627, and acko.com disclaimer page, read 19 October 2026
- Care Supreme prospectus, UIN CHIHLIP27061V032627; HDFC ERGO my: Optima Secure prospectus and brochure, UIN HDFHLIP26058V082526
- IRDAI (Insurance Products) Regulations, 2024, Schedule III, paragraph 7 (36-month maximum pre-existing disease wait)
- Claim settlement and complaint ratios: IRDAI published data, three-year weighted average, latest available as of March 2026
ACKO Platinum at a glance
| What Platinum is | a plan inside ACKO's filed health product, not a product with its own UIN; ACKO's downloads page carries Platinum, Platinum Lite and Platinum Super Top-up wordings under ACKO Health III, UIN ACKHLIP27040V012627 (read 19 October 2026) |
|---|---|
| Insurer | ACKO General Insurance Limited, IRDAI registration 157, not ACKO Life (Platinum wording, read 19 October 2026) |
| Room rent and ICU | actual charges, no cap (Platinum wording, section 2.2, read 19 October 2026) |
| Consumables and other non-payable items | paid, under the built-in Waiver of Non-payable Medical Expenses (Platinum wording, section 2.12, read 19 October 2026) |
| Pre and post hospitalisation | up to 60 days before, 180 days after (Platinum wording, section 2.4, read 19 October 2026) |
| Specified-illness wait | waived, except cataract and non-infectious arthropathies for anyone insured above 50 (Platinum wording, section 2.13, read 19 October 2026) |
| Initial 30-day wait | waived (Platinum wording, section 2.15, read 19 October 2026) |
| Pre-existing disease wait | set by underwriting and printed on your schedule (Platinum wording, section 3.1.1, read 19 October 2026) |
| Restoration and bonus | none in the Platinum wording (read 19 October 2026) |
| Maternity | excluded, ectopic pregnancy excepted (Platinum wording, section 3.1.16, read 19 October 2026) |
| Entry age | from 91 days, no maximum entry age stated, no cover-ceasing age (ACKO Health III prospectus, read 19 October 2026) |
| Claim record | 95.4% of claims settled, 16.8 complaints per 10,000 claims (IRDAI published data, three-year weighted average, latest available as of March 2026) |
Platinum wording means ACKO's Health III (Platinum) policy wording, UIN ACKHLIP27040V012627. nyvo holds no ACKO premium quotes, so this page gives no ACKO price.
Book a call for advice on the best policy for you and your family
A salaried, IRDAI-certified nyvo advisor will look at your cover, flag the gaps that matter, and tell you plainly what to fix. No commission, no pressure.
A first in India
Buy policy from nyvo insurance with Claim Support Guarantee, otherwise money back.
16+ years in financial services. Former investment banker at Bank of America, Kotak Investment Banking, and SBICaps, and ex-CFO of slice. Founder of nyvo and Principal Officer – IRDAI Certified.