First in India
Claim Support Guarantee, otherwise your money back.
Buy through nyvo and we get your claim passed, otherwise refund your premium. We are putting our money on our claim service.
Limited Pay vs Regular Pay Term Insurance: Which Should You Choose?
Limited pay vs regular pay term insurance: yearly cash flow against total premium, how pay till 60 works, and which top term plans offer each payment term.
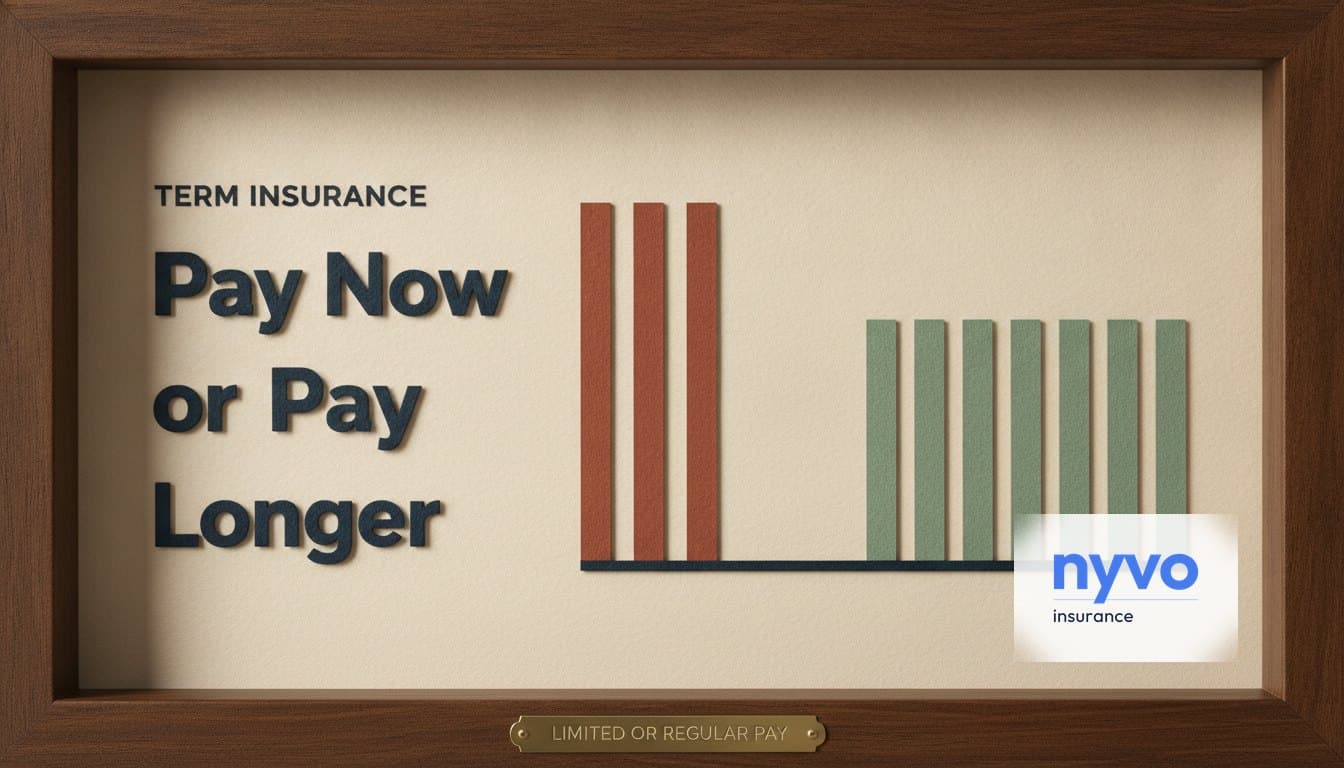
Limited pay or regular pay: which should you choose?
Regular pay spreads term insurance premiums over every year of cover; limited pay packs them into fewer, larger premiums, such as 10 years or until age 60. For ₹1 crore of cover to 60, a 30-year-old non-smoking man pays ₹9,528 a year on regular pay on the median of the five plans nyvo rates, ₹2,85,840 over 30 years (nyvo's premium data, May 2026).
Choose regular pay when your cover ends around the age your salary does, when you want the lowest yearly premium, and when you are not certain you will keep the policy for most of its term. Choose limited pay, usually as pay till 60, when your cover has to run past the age your salary stops, so that no premium falls due in retirement. nyvo's premium data prices regular pay only, so the limited-pay figures on this page come from an insurer's own illustration or from arithmetic on the published regular-pay premiums.
What is the premium payment term in term insurance?
The premium payment term is the number of years you pay premiums; the policy term is the number of years you are covered. On regular pay the two are the same. On limited pay you stop paying before the cover ends, for example 10 years of premiums for 30 years of cover. Single pay is one premium at the start.
| Payment option | You pay | You are covered |
|---|---|---|
| Regular pay | Every year of the policy term | For the same years |
| Limited pay | For a fixed number of years, such as 5, 10 or 15 | To the end of the policy term, years after the last premium |
| Pay till 60 | Every year until age 60 | To the end of the policy term, which can run past 60 |
| Single pay | Once, at the start | For the whole policy term |
The payment term is a cash-flow choice: it changes when you pay, not what your family receives. How long the cover itself should run is a separate decision, which our guide to term insurance tenure works through.
Which term plans offer limited pay, regular pay and single pay?
All five term plans nyvo rates offer regular pay and limited pay. Four also take a single premium; Bajaj Life eTouch II does not. Two list a pay till 60 option in nyvo's policy database, Axis Max Life Smart Term Plan Plus and Bajaj Life eTouch II, and both limit which variants and entry ages can use each payment option.
| Plan | Regular pay | Limited pay | Pay till 60 | Single pay |
|---|---|---|---|---|
| Axis Max Life Smart Term Plan Plus | Yes, except on the Smart Cover, Early ROP Plus and Whole Life Cover variants | 5, 7, 10, 12 or 15 years | Yes, for entry up to age 44 | Yes |
| Bajaj Life eTouch II | Yes, over the whole policy term | 5, 6, 10, 12, 15 or 20 years, finishing by age 75 | Yes, for entry from 18 to 55, or 25 to 55 on the return-of-premium variant | No |
| HDFC Life Click 2 Protect Supreme Plus | Yes | Yes; terms not recorded | Not recorded | Yes |
| ICICI Pru iProtect Smart Plus | Yes | Yes; terms not recorded | Not recorded | Yes |
| Tata AIA Sampoorna Raksha Promise | Yes | Yes; terms not recorded | Not recorded | Yes |
Payment options from each plan's brochure, prospectus or policy document (Smart Term Plan Plus UIN 104N127V05; eTouch II UIN 116N198V08; Click 2 Protect Supreme Plus UIN 101N189V01; iProtect Smart Plus UIN 105N205V04; Sampoorna Raksha Promise UIN 110N176V12), as recorded in nyvo's policy database. Not recorded means the database does not list it, not that the plan lacks it: ask for the exact terms on your quote.
Three rules change what you can choose:
- Axis Max Life Smart Term Plan Plus sells three of its six variants on limited terms only: Smart Cover, Early ROP Plus and Whole Life Cover.
- Bajaj Life eTouch II sells cover to age 99 only on limited pay, and on its return-of-premium variant with limited pay the policy term must run at least five years past the payment term.
- ICICI Pru iProtect Smart Plus lets you switch from regular to limited pay after three policy years, unless you bought a rider at the start; that rider blocks the switch for good.
Does limited pay cost less in total than regular pay?
Limited pay costs more each year and can cost fewer rupees in total, but only if you hold the policy long enough; leave early and you will have paid more. To test a quote, multiply the regular-pay premium by the years of cover and divide by the years of limited pay. A limited-pay premium below that figure costs fewer rupees in total; one above it costs more.
Worked through on published figures: on the median plan in nyvo's premium data (May 2026), a 30-year-old non-smoking man pays ₹9,528 a year for ₹1 crore of cover to 60, or ₹2,85,840 over 30 years of regular pay. For the same cover, a limited-pay premium adds up to that total at:
| Years of limited pay | Yearly premium that adds up to ₹2,85,840 |
|---|---|
| 5 | ₹57,168 |
| 10 | ₹28,584 |
| 15 | ₹19,056 |
| 20 | ₹14,292 |
These are break-even figures, not prices: nyvo's premium data does not price limited pay. Ask for both quotes on the same plan, cover and policy term, then run the test on your own numbers.
One insurer publishes a limited-pay figure. In the Smart Term Plan Plus prospectus, Axis Max Life shows a 30-year-old buying ₹1 crore of level cover to age 70 (the variant it calls Regular Cover) paying ₹30,810 a year over a 10-year payment term: ₹3,08,100 in all, with nothing to pay after the tenth premium (prospectus illustration, UIN 104N127V05, as recorded in nyvo's policy database). Spread over the 40 years of cover, that total is ₹7,702.50 a year, so a regular-pay quote for the same cover to 70 would need to be below that to cost fewer rupees in total.
Rupee totals flatter limited pay. A rupee you pay at 30 costs you more than a rupee you pay at 55: money paid early cannot earn anything for you in the meantime, and inflation shrinks the weight of a fixed premium paid later. A limited-pay total that only just undercuts regular pay is not a real saving.
An early exit favours regular pay. Each limited-pay premium is larger, so at any point before the limited term ends you have paid more than regular pay would have charged. If the policy ends early, because you replace it, stop paying or die within the paying years, limited pay will have cost more for the same years of cover.
Limited pay vs regular pay at a glance
| Regular pay, median of five plans | ₹9,528 a year, or ₹2,85,840 over 30 years |
|---|---|
| Break-even on 10 years of limited pay | ₹28,584 a year, if the policy is held all 30 years; a 10-pay quote above that costs more in total |
| The test for any quote | Regular-pay premium times years of cover, divided by years of limited pay |
| Pay till 60 entry age | Up to 44 on Axis Max Life Smart Term Plan Plus; 55 on Bajaj Life eTouch II |
| Single premium | Offered by four of the five plans nyvo rates; not by Bajaj Life eTouch II |
| Cover increases on ICICI Pru | Regular pay only |
Premiums: nyvo's premium data, May 2026: age 30, non-smoking man, ₹1 crore of cover to 60, regular pay; the median is of the five plans nyvo rates. Plan terms from nyvo's policy database.
When does limited pay make sense?
Limited pay makes sense when your cover has to run past the age your salary stops, or when you would rather finish paying while you are earning. A salaried buyer who needs cover to 65 or 70, for a home loan that runs late or children who will still be young, can pay till 60 and carry no premium into retirement.
- Cover that runs past retirement. Pay till 60, or a limited term that ends before you stop work, keeps every premium inside your earning years.
- Variants sold only on limited terms. On Axis Max Life Smart Term Plan Plus, Smart Cover (150% of the cover if death comes in the first 15 policy years), Early ROP Plus and Whole Life Cover cannot be bought on regular pay. On Bajaj Life eTouch II, cover to age 99 is sold only on limited pay, though cover that long is more than most families need.
- Income you expect to drop. A planned career break or an early retirement is a reason to finish paying before it starts.
- Money you want to commit now. A bonus can fund a short payment term, or a single premium on the four plans that take one, if you are sure you will keep the cover.
When is regular pay the better choice?
Regular pay is the better choice when your cover ends near retirement, when your salary should keep rising, and when you want the lowest yearly premium. It commits the least money up front, costs least if the policy ends early, and keeps the features that work only while premiums are still due, including a waiver of premium and a year's premium deferral.
- Cover that ends at 60. If the policy term ends at 60, pay till 60 and regular pay are the same schedule.
- A rising salary. A level premium takes a smaller share of a salary that grows, so regular pay gets lighter each year you hold it.
- Cover increases on ICICI Pru. iProtect Smart Plus raises cover by up to 100% on a home loan, 50% on marriage and 25% for each child, on regular-pay policies only.
- More years for premium-linked features. A waiver of premium and the plans' premium-deferral options work only while premiums are due; the table further down sets out how each plan's rules meet the payment term.
What is pay till 60, and which plans offer it?
Pay till 60 is a limited payment term that ends at age 60 while the cover runs on, to 70 or 75 for example, so it differs from regular pay only when cover runs past 60. Every plan in nyvo's policy database that offers it caps entry below the plan's usual limit: up to 44 on Axis Max Life Smart Term Plan Plus, 55 on Bajaj Life eTouch II. The table sets out six such plans.
| Plan | Pay till 60 open to entry age | Usual entry limit |
|---|---|---|
| Axis Max Life Smart Term Plan Plus | Up to 44 | 65 |
| Bajaj Life eTouch II | 18 to 55; 25 to 55 on the return-of-premium variant | 65 |
| Axis Max Life Smart Secure Plus Plan | Up to 44 | 65 |
| Axis Max Life Smart Total Elite Protection Plan | Up to 44 | 65 |
| Canara HSBC iSelect Smart360 Term Plan | Up to 55 on Life Secure; 50 on the income and return-of-premium options | 65 |
| Canara HSBC Young Term Plan | Up to 55 on Life Secure; 50 with return of premium | 60 |
Entry ages from each plan's prospectus or brochure (UINs 104N127V05, 116N198V08, 104N118V13, 104N125V06, 136N080V02 and 136N087V03), as recorded in nyvo's policy database. The first two are among the five plans nyvo rates. Canara HSBC iSelect Smart360 sets the payment term at 60 minus your entry age, with at least five years of premiums.
The years of premium shrink as you age. Pay till 60 bought at 30 means 30 years of premiums; at 44, the last entry age Axis Max Life accepts, 16; at 55 on Bajaj Life eTouch II, 5. Fewer years of premium for the same cover means a larger premium each year.
For a salaried buyer, pay till 60 is the simplest way to hold cover past retirement without a premium in retirement. If your cover ends at 60 anyway, regular pay already does that. Buying in your forties? Our guide to term insurance after 40 covers what else changes.
How does the payment term affect riders and other features?
The payment term decides how long premium-linked features can work. A waiver of premium can only waive premiums still due, and an option to defer a year's premium needs premiums left to defer, so a short limited term narrows both. Each of the five plans nyvo rates ties at least one such feature to the years you are still paying.
| Plan | Feature | How the payment term limits it |
|---|---|---|
| Axis Max Life Smart Term Plan Plus | Waiver of Premium Plus rider | Never runs past the premium term left on the base plan; not sold on Single Pay |
| Axis Max Life Smart Term Plan Plus | Cover Continuance: defer a year's premium after 3 full years | Never in the last year of the premium term |
| ICICI Pru iProtect Smart Plus | Premium Break: defer a year's premium after 5 policy years | Not in the last 3 years of the premium term |
| Tata AIA Sampoorna Raksha Promise | FlexiPay: defer 12 months of premium | Needs premiums still due once 5 full years are paid |
| Tata AIA Sampoorna Raksha Promise | 12-month premium holiday in pregnancy | After 2 years' premiums, up to twice in the premium term |
| Bajaj Life eTouch II | Premium Holiday: skip 1, 2 or 3 years of premium | Chosen at purchase; policy term and payment term must both be 20 years or more |
| HDFC Life Click 2 Protect Supreme Plus | Defer one year's premium | Needs premiums still due after 5 policy years, or 2 for women in the cases the plan names |
Feature terms from nyvo's policy database, from each plan's own documents. A feature that defers or waives premiums has nothing to work on once the last premium is paid, so a short limited term leaves little or no room for it.
Our guide to the waiver of premium rider shows what a waiver is worth on each schedule.
Want both schedules priced? A nyvo advisor can quote the same plan on each payment term it offers, for your age and cover, and run the break-even test with you. Book a free call. It costs you nothing; here is how nyvo is paid.
FAQs
Is limited pay better than regular pay for term insurance?
Not automatically. Limited pay costs more each year and can cost fewer rupees in total only if you hold the policy long enough, so it suits cover that runs past the age your salary stops. If your cover ends near retirement, regular pay keeps the yearly premium lowest: ₹9,528 a year on the median plan for ₹1 crore of cover to 60 bought at 30 (nyvo's premium data, May 2026).
What is the premium payment term in term insurance?
The premium payment term is how many years you pay premiums; the policy term is how many years you are covered. On regular pay the two are equal. On limited pay, such as 10 years or pay till 60, you stop paying before the cover ends, and on single pay you pay once at the start.
What does pay till 60 mean in a term plan?
It means you pay premiums every year until age 60 while the cover runs on to the end of the policy term, such as 70 or 75. Axis Max Life Smart Term Plan Plus offers it for entry up to age 44 and Bajaj Life eTouch II for entry from 18 to 55. If your cover ends at 60, it is the same as regular pay.
Does limited pay cost less in total?
It can, if you hold the policy long enough. Multiply the regular-pay premium by the years of cover and divide by the years of limited pay; a limited-pay quote below that figure costs fewer rupees in total. For ₹1 crore of cover to 60 bought at 30, the median regular-pay total is ₹2,85,840, so a 10-year quote would need to be below ₹28,584 a year (nyvo's premium data, May 2026).
Can I switch from regular pay to limited pay later?
Only on one of the five plans nyvo rates. ICICI Pru iProtect Smart Plus allows the switch after three policy years, but not if you bought a rider when the policy started. nyvo's policy database records no such switch on the other four, so treat the payment term you choose at purchase as fixed.
Can I pay a single premium for term insurance?
Yes, on four of the five plans nyvo rates: Axis Max Life Smart Term Plan Plus, HDFC Life Click 2 Protect Supreme Plus, ICICI Pru iProtect Smart Plus and Tata AIA Sampoorna Raksha Promise. Bajaj Life eTouch II has no single-premium option. A single premium leaves nothing for a waiver of premium to waive, and Axis Max Life does not sell its waiver on single pay.
Is pay till 60 better than regular pay?
Only when your cover runs past 60. If the policy term ends at 60, the two are the same schedule. If cover runs to 70 or 75, pay till 60 costs more each year but stops at 60, so no premium falls due in retirement; run the same break-even test on both quotes before you choose.
Related Guides
Book a call for advice on the best policy for you and your family
A salaried, IRDAI-certified nyvo advisor will look at your cover, flag the gaps that matter, and tell you plainly what to fix. No commission, no pressure.
A first in India
Buy policy from nyvo insurance with Claim Support Guarantee, otherwise money back.
16+ years in financial services. Former investment banker at Bank of America, Kotak Investment Banking, and SBICaps, and ex-CFO of slice. Founder of nyvo and Principal Officer – IRDAI Certified.